Data Center Liquid Cooling Market Overview: AI Infrastructure Expansion, Direct-to-Chip Cooling and High-Density Thermal Management
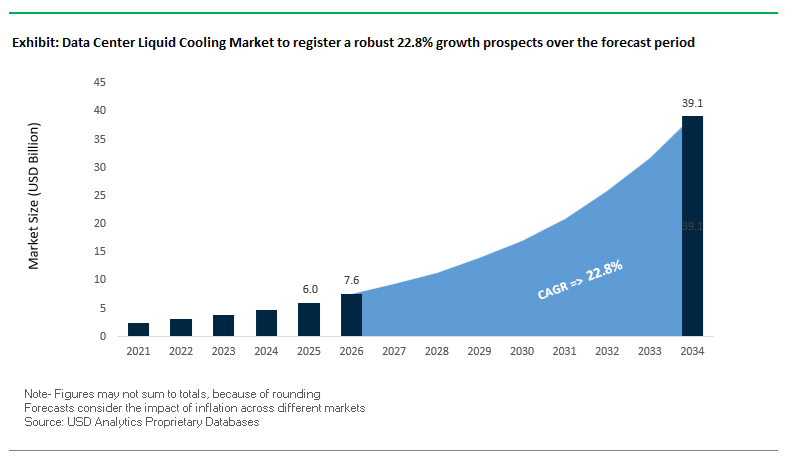
The global Data Center Liquid Cooling Market is valued at USD 7.6 billion in 2026 and is projected to reach USD 39.1 billion by 2034, with a stated CAGR of 22.8% over the forecast period. Data center liquid cooling encompasses advanced thermal management solutions that use liquid coolants to remove heat from high-density computing equipment, including AI accelerators, graphics processing units (GPUs), CPUs and high-performance computing (HPC) servers. The market covers direct-to-chip liquid cooling, cold-plate systems, immersion cooling, spray liquid cooling, coolant distribution units (CDUs), heat exchangers, fluid distribution infrastructure and associated engineering services. Unlike conventional air cooling, liquid-based thermal architectures enable concentrated heat removal from high-power components while integrating with facility-level heat rejection systems. Commercial deployment spans hyperscale data centers, cloud computing infrastructure, colocation facilities and enterprise computing environments, with cooling configurations determined by processor heat flux, rack power density, facility design and operational requirements.
The expansion of AI data centers, generative AI workloads and accelerated computing infrastructure is reshaping demand for high-capacity liquid cooling systems as increasing processor thermal design power and server rack density place greater demands on conventional air-based heat removal. The International Energy Agency reported a 17% increase in global data center electricity consumption during 2025, reflecting the broader expansion of power-intensive digital infrastructure. AI accelerator architectures increasingly incorporate direct liquid cooling to manage concentrated processor heat loads, creating demand for cold-plate assemblies, coolant distribution systems and compatible rack-level infrastructure. Direct-to-chip cooling is particularly relevant to GPU-dense deployments because cold plates transfer heat from high-power processors into circulating coolant, while immersion cooling provides an alternative architecture for systems designed around dielectric-fluid heat transfer. Market adoption is also influenced by liquid-cooling retrofits in existing data centers, hybrid air-liquid cooling configurations, cooling energy consumption and the increasing integration of CDU capacity with AI server deployment schedules.
The competitive structure of the data center liquid cooling industry comprises thermal management equipment manufacturers, specialist liquid-cooling technology providers, fluid-handling component suppliers and engineering service providers. Solutions represent the largest component category, while the market also includes design and consulting, installation and deployment, and support and maintenance services. Commercial differentiation increasingly centers on high-capacity CDUs, cold-plate thermal performance, coolant compatibility, leak detection, redundant pumping configurations, system reliability and integration with hyperscale data center infrastructure. The introduction of multi-megawatt coolant distribution platforms, including Motivair's 2.5 MW MCDU-70 and Vertiv's 2.3 MW CoolChip CDU, demonstrates the progression toward larger liquid-cooling installations supporting AI and HPC workloads. Regional deployment patterns reflect differences in hyperscale construction, colocation capacity expansion, electricity infrastructure, cooling-water availability and the economics of integrating liquid-based thermal systems into new-build and existing facilities.
Key Insights: Data Center Liquid Cooling Market
- Cold Plate Liquid Cooling Leads Technology Demand: Direct-to-chip cooling dominates technology adoption, supported by liquid-cooled AI servers, high-density GPU clusters and compatibility with conventional rack infrastructure.
- Hyperscale Data Centers Dominate End-User Demand: Hyperscale facilities represent the largest end-user segment, while cloud providers and colocation operators contribute demand for AI computing and high-density hosting.
- AI Accelerator Power Density Supports Cooling Infrastructure Expansion: Increasing GPU thermal loads drive demand for cold plates, rack manifolds, coolant distribution units (CDUs) and high-capacity liquid-cooling systems.
- Multi-Megawatt CDUs Reshape Equipment Competition: Vertiv and Motivair offer 2.3 MW and 2.5 MW CDU platforms, respectively, reflecting growing demand for modular cooling capacity and system interoperability.
- Hybrid Liquid Cooling Expands Brownfield Applications: Liquid-to-air cooling and retrofit-compatible CDUs enable liquid-cooled AI server deployments within existing facilities, including Google's 60 kW Brazos rack-cooling architecture.
- Cooling Economics and Reliability Influence Supplier Differentiation: Cooling energy consumption, infrastructure costs, coolant compatibility, leakage management, maintenance requirements and system uptime influence equipment selection and lifecycle expenditure.
Recent Developments and Company Strategies in the Data Center Liquid Cooling Market
The Data Center Liquid Cooling Market has recorded significant developments in high-capacity thermal management, coolant distribution technology and advanced processor cooling during 2025–2026. In October 2026, DCX Liquid Cooling Systems introduced integrated coolant-quality monitoring and automated chemical treatment across its 5–8 MW Facility Distribution Unit (FDU) family, incorporating inline sensors and electronic dosing controls for coolant chemistry management. The company's facility-scale coolant management development combines continuous monitoring of parameters including pH, conductivity, glycol concentration and corrosion indicators with automated treatment using inhibitors, biocides and pH-control additives. On October 13, 2026, ZutaCore unveiled its Two-Phase Matrix Flow Boiling technology for OmniTherm cold plates, using distributed boiling regions to manage localized thermal loads in high-performance AI processors. The company also reported initial OmniTherm deployments involving NVIDIA RTX PRO 6000 Blackwell Server Edition GPUs. These developments extend liquid-cooling technology beyond heat-transfer capacity toward processor-level temperature control, coolant reliability and integrated thermal-system management.
Development activity has also accelerated in multi-megawatt coolant distribution units (CDUs) designed for hyperscale data centers and AI computing infrastructure. In September 2026, Trane Technologies introduced the LiquidStack CDU 2.X platform, delivering up to 2.5 MW of cooling capacity with a configurable architecture supporting changing coolant flow and pressure requirements. During the same month, Vertiv announced that its 2.3 MW CoolChip CDU had qualified under NVIDIA's DSX Ready program, linking liquid-cooling equipment qualification more closely with AI factory reference architectures. Earlier, in May 2026, LiquidStack announced commercial availability of its GigaModular CDU platform, offering modular cooling infrastructure scalable to 14 MW, while Motivair by Schneider Electric introduced its 2.5 MW MCDU-70 in January 2026, with centrally managed configurations capable of scaling beyond 10 MW. These product introductions reflect increasing differentiation through cooling capacity, hydraulic performance, modular expansion, system redundancy and compatibility with successive generations of AI accelerators.
Liquid-cooling commercialization has expanded into hybrid cooling systems, retrofit solutions and integrated data center infrastructure. In June 2026, Google introduced Project Brazos, a rack-mounted liquid-to-air cooling system, enabling liquid-cooled computing equipment to operate within existing air-cooled facilities without requiring a facility-wide liquid distribution conversion. The system was announced as generally available, with manufacturing suppliers prepared to support broader industry adoption. In August 2026, Trane Technologies and Eaton announced a collaboration on an integrated power and thermal-management reference design aligned with NVIDIA DSX AI Factory architecture, combining electrical distribution and cooling infrastructure within a coordinated facility design. Vertiv introduced its MegaMod HDX configurations in January 2026, integrating direct-to-chip liquid cooling with air-based thermal management in prefabricated data center modules offering capacity up to 10 MW. Meanwhile, Alfa Laval launched FreeWaterLoop in March 2026, combining pumping systems, heat exchangers and filtration within an integrated facility-loop cooling platform designed to use natural water sources for heat rejection.
Manufacturing expansion and corporate consolidation have accompanied the growing commercialization of direct liquid cooling, cold plates, CDUs and hyperscale thermal-management equipment. In February 2026, Schneider Electric launched a Motivair liquid-cooling manufacturing facility in Bengaluru, establishing its third global production location for the technology alongside facilities in the United States and Italy. During the same month, CoolIT Systems reported substantial expansion of its manufacturing capabilities across Canada, China and Vietnam, with monthly production reaching hundreds of CDUs, thousands of rack manifolds and tens of thousands of cold-plate loops. In March 2026, Trane Technologies completed its acquisition of LiquidStack, adding specialist direct-to-chip and immersion-cooling capabilities to its broader data center thermal-management portfolio. The expansion of production capacity has also been accompanied by advances in component engineering, including CoolIT Systems' June 2026 demonstration of a 15 kW single-phase cold-plate design intended to address future high-heat-flux processor requirements.
Developments in immersion cooling, dielectric fluids and lifecycle thermal-management services illustrate the widening commercial scope of liquid-cooled data center infrastructure. In September 2026, Vertiv announced an agreement to acquire King Environmental Services, a specialist in fluid management, commissioning and load testing, following its completed acquisition of PurgeRite in December 2025 for approximately USD 1.0 billion. The proposed King Environmental Services transaction remained subject to completion as announced. In March 2026, Green Revolution Cooling (GRC) and UNICOM Engineering expanded their collaboration to deliver integrated single-phase immersion-cooled systems for AI, high-performance computing and distributed industrial computing environments. In the coolant materials segment, Chemours, NTT DATA and Hibiya Engineering initiated a full-scale trial of Opteon 2P50 dielectric fluid for two-phase immersion cooling in March 2025. Technical qualification activity also expanded through the Open Compute Project, whose 2026 contributions included specifications for single-phase direct-to-chip cold-plate testing, universal quick-disconnect interfaces and dielectric heat-transfer fluids, covering component interoperability, coolant compatibility and thermal-system validation.
Regulatory and Technical Standards for Data Center Liquid Cooling Systems
The Data Center Liquid Cooling Market is influenced by energy-efficiency reporting requirements, water conservation policies and data center sustainability standards. The European Union's Energy Efficiency Directive (EU) 2023/1791 establishes annual reporting obligations for qualifying data centers with installed IT power demand of at least 500 kW, subject to specified exemptions. Reporting covers energy consumption, water usage and waste heat utilization without mandating a particular cooling technology. ISO/IEC 30134-2:2026 and ISO/IEC 30134-9:2022 establish standardized methodologies for measuring Power Usage Effectiveness (PUE) and Water Usage Effectiveness (WUE), respectively.
Technical qualification is particularly relevant to direct-to-chip cooling, immersion cooling and coolant distribution units (CDUs). The Open Compute Project Cooling Environments initiative develops industry specifications addressing cold-plate performance, coolant compatibility, quick-disconnect interfaces and liquid-cooling system integration. These voluntary specifications support equipment interoperability and consistent qualification across high-density AI and hyperscale data center infrastructure, where thermal performance, leakage prevention and operational reliability influence supplier selection and system integration.
AI GPU Rack Power Density Accelerates Direct-to-Chip Liquid Cooling Demand
Increasing processor thermal design power and AI server rack density are strengthening demand for direct-to-chip liquid cooling, cold-plate assemblies and high-capacity thermal management systems. The International Energy Agency reported that electricity consumption at AI-focused data centers increased 50% in 2025, while capacity at advanced AI factories more than tripled over the preceding 18 months. NVIDIA's fully liquid-cooled GB300 NVL72 architecture integrates 72 Blackwell Ultra GPUs and 36 Grace CPUs within a rack-scale computing system, illustrating the concentration of processor heat loads in accelerated computing infrastructure. Direct-to-chip cooling transfers heat from CPUs and GPUs through liquid-cooled cold plates, reducing dependence on air as the primary heat-transfer medium for these components. Increasing chip-level thermal loads are also expanding the commercial relevance of precision cold plates, rack manifolds, quick-disconnect connectors and high-flow coolant distribution systems across hyperscale AI clusters and high-performance computing installations.
Data Center Cooling Energy Costs and Total Cost of Ownership Influence Liquid Cooling Adoption
Cooling energy consumption, infrastructure costs and total cost of ownership (TCO) remain important commercial factors in the adoption of liquid-cooled data center infrastructure. The Uptime Institute's 2025 Global Data Center Survey identified costs among operators' leading concerns and reported limited improvement in average Power Usage Effectiveness (PUE) over six consecutive years. Liquid-cooling economics depend on the relationship between initial equipment expenditure, CDU pumping energy, facility heat rejection, electrical infrastructure, coolant maintenance and available IT capacity. The Open Compute Project's liquid-cooled data center TCO model enables comparative assessment of capital expenditure (CapEx) and operating expenditure (OpEx) across new-build and retrofit configurations. Economic outcomes vary according to rack density, climate, electricity tariffs, cooling architecture and facility utilization. At higher computing densities, the allocation of floor space, auxiliary cooling power and equipment maintenance costs becomes increasingly relevant to lifecycle cost comparisons between conventional air cooling, direct-to-chip systems and immersion cooling.
Multi-Megawatt Coolant Distribution Units and Modular Liquid Cooling Infrastructure Gain Momentum
The Data Center Liquid Cooling Market is experiencing a shift toward multi-megawatt coolant distribution units (CDUs), modular cooling platforms and standardized hydraulic interfaces for AI and hyperscale deployments. In 2026, manufacturers expanded their equipment portfolios beyond conventional rack-level cooling toward centralized and end-of-row architectures supporting higher coolant flow rates, greater heat-exchanger capacity and configurable system redundancy. CDU performance is increasingly defined by cooling capacity, available differential pressure, flow rate, approach temperature and compatibility with liquid-cooled GPU systems. Industry standardization is progressing through Open Compute Project specifications for cold-plate testing, universal quick-disconnect couplings and coolant interfaces. Manufacturing differentiation also extends to modular assembly, factory testing, monitoring integration and maintainable pumping configurations.
Selected 2026 Data Center Liquid Cooling Equipment Capacities
|
Manufacturer / Platform
|
Announced Capacity
|
Configuration
|
|
Vertiv CoolChip CDU 2300
|
2.3 MW
|
Single liquid-to-liquid CDU; NVIDIA DSX Ready qualification
|
|
Motivair MCDU-70
|
2.5 MW
|
Single CDU; centralized configurations scalable beyond 10 MW
|
|
LiquidStack GigaModular
|
Up to 14 MW
|
Modular multi-unit CDU platform using 2.5 MW building blocks
|
Source: Official manufacturer specifications and 2026 announcements. Capacities represent manufacturer-stated ratings under different operating conditions; single-unit and modular-platform figures are not directly equivalent.
Single-Phase and Two-Phase Liquid Cooling Technologies Advance Alongside New Coolant Formulations
Technology development in single-phase direct liquid cooling, two-phase cold-plate systems and immersion cooling is increasing differentiation across the data center thermal-management supply chain. Single-phase systems commonly circulate treated water or water-glycol mixtures through cold plates, while two-phase configurations use coolant phase change to absorb heat from high-power electronic components. The Open Compute Project released multiple specifications in 2026 covering water-based cold-plate fluids, PG25 glycol formulations, two-phase dielectric heat-transfer fluids and material compatibility. Commercial coolant portfolios are also expanding, with Castrol receiving OCP Inspired recognition for its PG25 direct liquid-cooling fluid in May 2026, alongside specialist offerings from Shell, Perstorp and Chemours. PFAS-free synthetic esters and alternative dielectric fluids are gaining attention due to fluid longevity, electrical insulation, fire safety and environmental considerations. However, fluorinated formulations remain under development for selected applications, making fluid selection dependent on specific thermal architectures, component qualification and lifecycle performance.
Brownfield Data Center Retrofits Expand the Market for Hybrid Air-Liquid Cooling Systems
Existing enterprise and colocation facilities represent an expanding application segment for hybrid air-liquid cooling, rack-mounted CDUs and retrofit-ready direct-to-chip cooling systems. Facility conversion is influenced by available electrical capacity, mechanical space, existing cooling infrastructure and compatibility with liquid-cooled AI servers. In June 2026, Google introduced Brazos, a generally available, rack-mounted liquid-to-air cooling architecture that transfers heat from liquid-cooled IT equipment into an existing data center's air-handling environment. The system supports a nominal 60 kW thermal load per rack, using three modular cooling units, and operates with deionized water or a 25% propylene glycol mixture. Unlike facility-wide liquid-loop conversions, this architecture enables rack-level deployment where sufficient air-handling and electrical capacity already exist. Commercial demand encompasses compact CDUs, liquid-to-air heat exchangers, rack manifolds, fluid distribution components and associated installation services, particularly in facilities undergoing phased AI server upgrades.
Warm-Water Liquid Cooling and Waste Heat Recovery Expand Commercial Applications
Warm-water liquid cooling, heat recovery and facility-side thermal integration are creating additional commercial applications for data center cooling infrastructure. Higher operating coolant temperatures can expand the use of economizers and dry-cooling systems under suitable climatic and equipment conditions, while heat exchangers and industrial heat pumps enable captured server heat to serve external heating networks. LiquidStack's CDU 2.X platform supports facility inlet temperatures up to 45°C, demonstrating equipment development around warmer cooling loops. The European Commission's September 2026 assessment reported that only 67 data centers declared waste heat reuse during the first EU reporting period, with approximately 1.8% of generated heat reused in the assessed dataset, subject to reporting limitations. Finland provides a large-scale integration example: Fortum commissioned heat pump infrastructure at two Microsoft data center sites in May 2026, with data-center waste heat integration scheduled to begin in phases in 2027. The project incorporates water-to-water heat pumps providing up to 180 MW of district-heating capacity, alongside thermal storage and electric boilers.
Data Center Liquid Cooling Market Share Analysis by Type and End-User
By Type: Cold Plate Liquid Cooling Leads with Direct-to-Chip Adoption in AI Data Centers
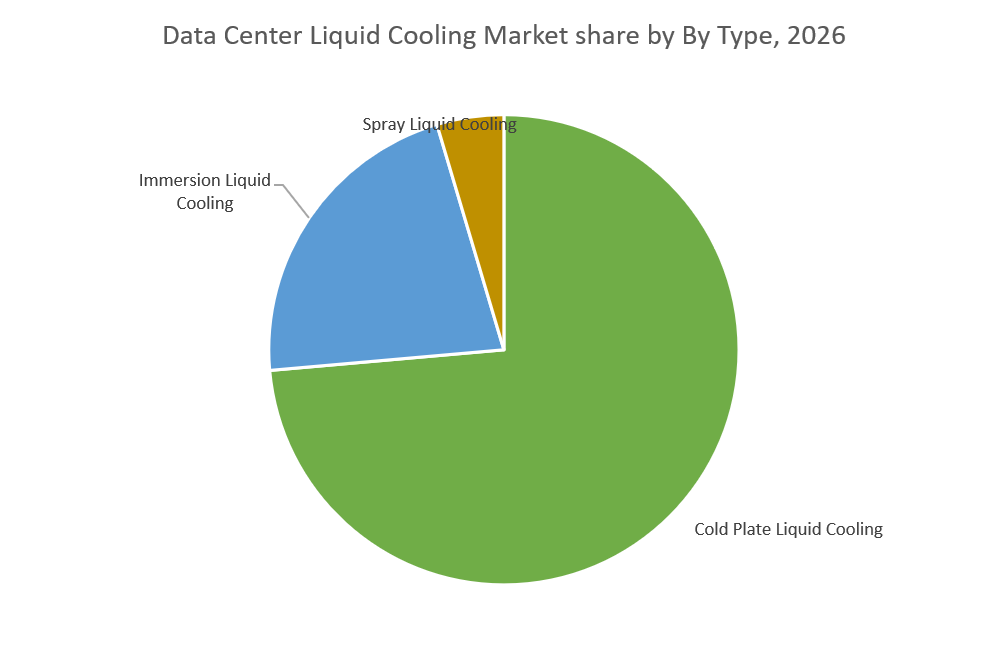
Cold Plate Liquid Cooling dominates the Data Center Liquid Cooling Market, accounting for an estimated 75% market share in 2026. Its leading position reflects widespread integration of direct-to-chip cooling technologies into AI servers, GPU-intensive computing clusters and hyperscale data center infrastructure. Cold-plate systems enable targeted heat removal from high-performance processors while maintaining compatibility with conventional server racks, coolant distribution units (CDUs) and existing facility cooling architectures. The commercialization of NVIDIA Blackwell-based liquid-cooled systems and increasing availability of multi-megawatt CDUs reinforce the segment's competitive position. Immersion cooling maintains a presence in specialized high-density computing applications, while spray cooling remains comparatively limited in commercial deployment.
By End-User: Hyperscale Data Centers Lead as Cloud Providers Expand Liquid Cooling Deployment
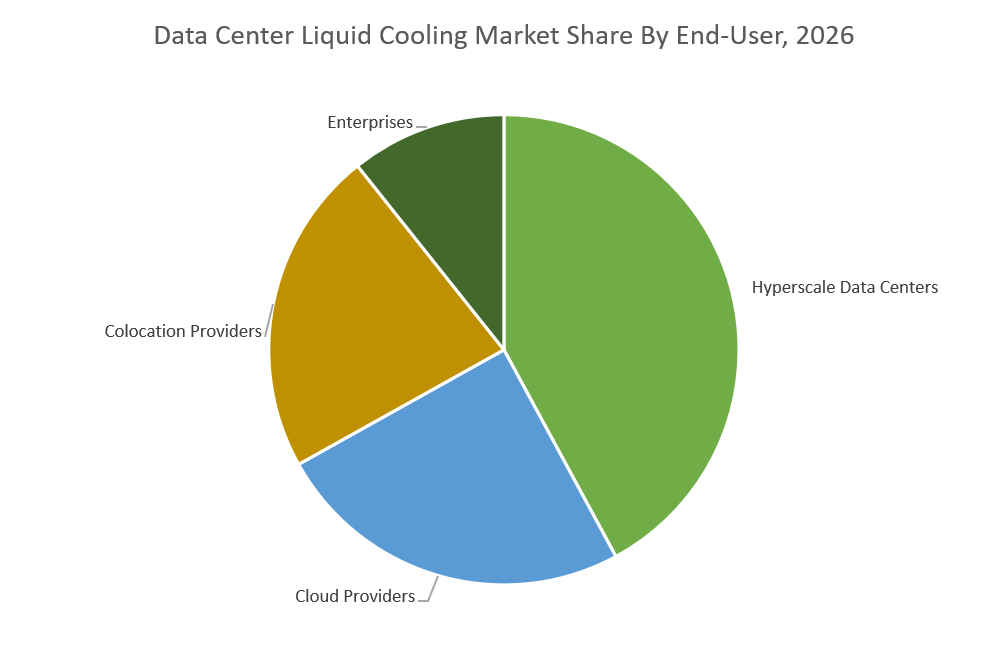
Hyperscale Data Centers represent the largest end-user segment, accounting for an estimated 45% market share in 2026, supported by large-scale AI infrastructure expansion, high-density GPU clusters and increasing deployment of liquid-cooled computing platforms. Hyperscale facilities generate substantial demand for direct-to-chip cooling systems, centralized coolant distribution and modular thermal-management infrastructure capable of supporting high-power server configurations. Cloud Providers account for an estimated 20% share, representing non-hyperscale cloud operators, specialized AI cloud platforms and GPU-as-a-service providers in this segmentation. Demand from these operators is associated with accelerated computing, AI inference workloads and scalable cooling infrastructure. Colocation providers contribute through high-density hosting facilities and retrofit projects, while enterprise adoption remains concentrated in private AI computing, HPC and specialized industrial workloads.
Data Center Liquid Cooling Market Competitive Landscape: Direct-to-Chip, CDU and Immersion Cooling Suppliers
The global Data Center Liquid Cooling Market is characterized by competition among integrated thermal management companies, direct-to-chip cooling specialists, immersion cooling technology providers and data center infrastructure suppliers. Vertiv, Schneider Electric (Motivair), Trane Technologies (LiquidStack), Daikin Applied (Chilldyne), STULZ and Rittal compete across coolant distribution units (CDUs), facility cooling integration and high-density AI data center infrastructure. Vertiv's CoolChip CDU portfolio includes configurations with capacities up to 2.3 MW, while Motivair's MCDU-70 delivers up to 2.5 MW per unit. Trane Technologies' acquisition of LiquidStack in March 2026 and Daikin Applied's acquisition of Chilldyne in November 2025 have expanded their capabilities across chip-level cooling, coolant distribution and facility thermal management.
Competition in direct-to-chip liquid cooling systems and high-capacity CDUs includes CoolIT Systems, Boyd, DCX Liquid Cooling Systems and Delta Electronics, with differentiation centered on cold-plate performance, coolant flow rates, hydraulic pressure, modularity and equipment qualification. CoolIT's CHx2000 and Boyd's ROL4000 platforms each provide manufacturer-rated cooling capacities of 2 MW, while Delta's GoCool liquid-to-liquid CDU portfolio includes a 3 MW configuration. DCX has expanded into facility-scale cooling with its FDU platform, offering rated heat-transfer capacity up to 8.15 MW. These manufacturers serve AI accelerator platforms, hyperscale computing facilities and high-performance computing installations through combinations of liquid-cooling hardware, system controls and component integration.
The immersion cooling and advanced dielectric liquid-cooling segment includes Submer, Green Revolution Cooling (GRC), Iceotope and ZutaCore, which compete through differentiated heat-transfer architectures, server compatibility and thermal performance. Submer's SmartPod EXO supports manufacturer-rated heat dissipation up to 361 kW, while GRC's ICEraQ portfolio encompasses modular immersion systems for hyperscale, enterprise and edge deployments. Iceotope focuses on precision liquid-cooling technology and OEM integration, whereas ZutaCore specializes in waterless, two-phase direct-to-chip cooling using dielectric fluids. Competitive differentiation in these technologies is associated with coolant chemistry, heat flux management, maintenance requirements, rack integration and operating economics.
At the facility infrastructure level, Alfa Laval competes through liquid-based heat exchange, pumping, filtration and heat-rejection technologies, including its FreeWaterLoop platform introduced in March 2026. Across the wider data center liquid cooling industry, competitive positioning is increasingly linked to multi-megawatt cooling capacity, cold-plate compatibility with AI processors, coolant distribution reliability, manufacturing scale and integration with existing data center infrastructure. Equipment suppliers also differ in their coverage of engineering, installation, commissioning, fluid management and aftermarket services, while collaboration with server OEMs, semiconductor platform providers and hyperscale operators remains an important feature of technology qualification and commercial deployment.
Data Center Liquid Cooling Market Geographical Analysis: AI Infrastructure Expansion and Regional Technology Adoption
United States Data Center Liquid Cooling Market: Hyperscale AI Infrastructure and High-Density Cooling Deployment
The United States Data Center Liquid Cooling Market is supported by large-scale hyperscale data center expansion, AI accelerator deployments and an established ecosystem of thermal management equipment manufacturers. In May 2026, Schneider Electric and Motivair announced phased delivery of more than USD 290 million in combined power and liquid-cooling infrastructure for TeraWulf's Lake Mariner campus in New York, which has a stated development capacity of 750 MW. The project reflects increasing integration of direct-to-chip cooling, coolant distribution units (CDUs) and electrical infrastructure in AI computing facilities. Domestic manufacturing by Motivair, CoolIT Systems and LiquidStack, alongside technology development by Vertiv, supports competition in high-capacity CDUs, cold-plate cooling systems, modular infrastructure and liquid-cooling services.
China Data Center Liquid Cooling Market: Cold-Plate Technology and Domestic AI Computing Infrastructure
China's Data Center Liquid Cooling Market is characterized by substantial AI computing infrastructure, domestic cooling-equipment manufacturing and growing deployment of energy-efficient thermal management systems. China Mobile's Hohhot Data Center operates liquid-cooled AI computing infrastructure using cold-plate technology for high-performance processors. Separately, China Mobile's Yangtze River Delta cloud computing facility in Suzhou reported a 50–60% reduction in cooling energy consumption following liquid-cooling deployment, with facility Power Usage Effectiveness (PUE) below 1.25. China's technology ecosystem includes Huawei Digital Power, Inspur, Sugon and domestic liquid-cooling component suppliers, supporting development of coolant distribution, server-level heat exchangers and integrated cooling infrastructure. Domestic technical standardization and telecommunications-led computing projects are important characteristics of the country's liquid-cooling equipment market.
Germany Data Center Liquid Cooling Market: CDU Manufacturing, Energy Efficiency and AI-Ready Colocation
Germany's Data Center Liquid Cooling Market is supported by high-density colocation development, domestic precision cooling manufacturing and stringent data center energy-efficiency requirements. In July 2025, STULZ established a dedicated liquid-cooling production line at its Hamburg headquarters for CyberCool CMU coolant distribution systems, expanding manufacturing capabilities for AI and high-performance computing applications. Maincubes lists its 16 MW FRA03 data center near Frankfurt as operational from June 2026, incorporating liquid-cooling readiness for high-density AI workloads. Germany's Energy Efficiency Act also establishes requirements concerning PUE and waste heat utilization for qualifying facilities, strengthening the relevance of efficient heat-rejection systems and thermal integration. Competition encompasses CDUs, liquid-to-chip cooling, precision cooling equipment, heat exchangers and waste heat recovery infrastructure.
Japan Data Center Liquid Cooling Market: Advanced AI Servers and Hybrid Thermal Management Systems
Japan's Data Center Liquid Cooling Market is gaining commercial relevance through AI computing infrastructure, direct liquid cooling integration and advanced facility thermal-management technologies. In January 2026, KDDI commenced operations at its Osaka Sakai AI Data Center, incorporating NVIDIA GB200 NVL72 systems with direct liquid cooling alongside conventional air-cooling infrastructure. The facility reuses electrical and cooling equipment from a former industrial manufacturing site, demonstrating the integration of high-density AI computing within existing infrastructure. KDDI, HPE, Daikin and NTT DATA participate in developments involving liquid-cooled server platforms, hybrid cooling configurations and integrated HVAC control technologies. The Japanese market also encompasses enterprise AI computing, high-performance computing clusters and liquid-cooling solutions adapted to space-constrained data center environments.
Singapore Data Center Liquid Cooling Market: High-Density Colocation and Tropical Climate Cooling Efficiency
Singapore's Data Center Liquid Cooling Market is influenced by limited land availability, high-density colocation demand, tropical operating conditions and government emphasis on sustainable digital infrastructure. In February 2026, Nxera, Singtel's data center business, opened its 58 MW DC Tuas facility, incorporating large-scale direct-to-chip liquid cooling for AI, cloud and high-performance computing workloads. The company reported that more than 90% of the facility's capacity was committed before opening, alongside a facility PUE of 1.25. The deployment combines liquid cooling with high-efficiency electrical systems, water recovery and thermal-management technologies suited to Singapore's climate. Commercial activity is concentrated in AI-ready colocation facilities, high-density GPU hosting, hybrid cooling architecture and energy-efficient data center infrastructure.
India Data Center Liquid Cooling Market: AI Data Center Expansion and Localized Cooling Equipment Manufacturing
India's Data Center Liquid Cooling Market is expanding through hyperscale and colocation infrastructure development, sovereign AI computing projects and localization of thermal-management equipment production. In February 2026, Schneider Electric inaugurated a Motivair liquid-cooling manufacturing facility in Bengaluru, establishing India's first production site for Motivair cooling technology and its third globally. During the same month, NxtGen AI and Vertiv announced an AI infrastructure deployment involving more than 4,000 NVIDIA Blackwell GPUs using Dell liquid-cooled servers, supported by high-capacity CDUs, modular secondary piping and heat-rejection equipment. Activity across Schneider Electric, Vertiv, NxtGen AI and domestic data center operators reflects growing demand for direct-to-chip liquid cooling, AI server thermal management, integrated power-cooling systems and locally manufactured cooling infrastructure.
Data Center Liquid Cooling Market Report Scope
Data Center Liquid Cooling Market Report Scope, Segmentation and Technology Coverage (2026–2034)
|
Parameter
|
Details
|
|
Market Size (2026)
|
USD 7.6 Billion
|
|
Market Size (2034)
|
USD 39.1 Billion
|
|
Market Growth Rate
|
CAGR of 22.8%
|
|
Segments
|
By Component: Solutions (Direct Liquid Cooling, Indirect Liquid Cooling), Services (Design and Consulting, Installation and Deployment, Support and Maintenance); By Type: Cold Plate Liquid Cooling, Immersion Liquid Cooling, Spray Liquid Cooling; By End-User: Cloud Providers, Colocation Providers, Enterprises, Hyperscale Data Centers
|
|
Study Period
|
Historical: 2020–2025; Forecast: 2026–2034
|
|
Units
|
Revenue (USD Billion)
|
|
Technology Coverage
|
Direct-to-Chip Liquid Cooling, Cold Plate Cooling, Single-Phase and Two-Phase Immersion Cooling, Spray Liquid Cooling, Coolant Distribution Units (CDUs), Liquid-to-Liquid and Liquid-to-Air Heat Exchangers, Coolant Management and Leak Detection Systems
|
|
Qualitative Analysis
|
Porter's Five Forces, SWOT Profiles, Market Share Analysis, Market Dynamics, Industry Benchmarking, Competitive Landscape, Market Ecosystem, Technology Trends and Regional Outlook
|
|
Regulatory & Standards Coverage
|
ASHRAE TC 9.9 Liquid Cooling Guidelines and Thermal Classes, ANSI/ASHRAE 90.4 (Data Center Energy Efficiency), ISO/IEC 30134-2 (Power Usage Effectiveness), EU Energy Efficiency Directive and Data Center Sustainability Reporting Requirements
|
|
Companies
|
Vertiv Holdings Co., Schneider Electric SE (Motivair), Trane Technologies plc (LiquidStack), CoolIT Systems Inc., Boyd Corporation, Delta Electronics Inc., DCX Liquid Cooling Systems, Daikin Industries Ltd. (Daikin Applied / Chilldyne), STULZ GmbH, Rittal GmbH & Co. KG, Alfa Laval AB, Submer, Green Revolution Cooling (GRC), Iceotope Technologies Ltd., ZutaCore Inc.
|
|
Countries
|
US, Canada, Mexico, Germany, France, Spain, Italy, UK, Russia, China, India, Japan, South Korea, Australia, Southeast Asia, Brazil, Argentina, Middle East, Africa
|
Data Center Liquid Cooling Market Segmentation
By Component
- Solutions
- Direct Liquid Cooling
- Indirect Liquid Cooling
- Services
- Design and Consulting
- Installation and Deployment
- Support and Maintenance
By Type
- Cold Plate Liquid Cooling
- Immersion Liquid Cooling
- Spray Liquid Cooling
By End-User
- Cloud Providers
- Colocation Providers
- Enterprises
- Hyperscale Data Centers
Countries Analyzed
- North America (US, Canada, Mexico)
- Europe (Germany, UK, France, Spain, Italy, Russia, Rest of Europe)
- Asia Pacific (China, India, Japan, South Korea, Australia, South East Asia, Rest of Asia)
- South America (Brazil, Argentina, Rest of South America)
- Middle East and Africa (Saudi Arabia, UAE, Rest of Middle East, South Africa, Egypt, Rest of Africa)
Leading players in Data Center Liquid Cooling Industry
- Vertiv Holdings Co.
- Schneider Electric SE (Motivair)
- Trane Technologies plc (LiquidStack)
- CoolIT Systems Inc.
- Boyd Corporation
- Delta Electronics Inc.
- DCX Liquid Cooling Systems
- Daikin Industries Ltd. (Daikin Applied / Chilldyne)
- STULZ GmbH
- Rittal GmbH & Co. KG
- Alfa Laval AB
- Submer
- Green Revolution Cooling (GRC)
- Iceotope Technologies Ltd.
- ZutaCore Inc.
*- List not Exhaustive
Data Center Liquid Cooling Market Research Methodology
The Data Center Liquid Cooling Market research incorporates a structured assessment of industry developments, technology adoption, competitive positioning and regional demand patterns. Secondary research draws on company annual reports, investor presentations, official product specifications, regulatory publications, industry associations and verified data center infrastructure announcements. The analysis covers direct-to-chip cooling, immersion cooling, spray liquid cooling, coolant distribution units (CDUs) and associated services, with particular attention to AI computing infrastructure, hyperscale deployments and high-density thermal management.
Market estimation and forecasting incorporate supply-side and demand-side assessments, supported by data triangulation and analysis of equipment deployments, manufacturing capacity, technology adoption and data center construction activity. The segmentation framework evaluates the market by component, type, end-user and geography, accounting for differences in cooling architecture, facility scale and commercial applications. Forecast analysis considers AI accelerator adoption, cooling infrastructure expenditure, energy-efficiency requirements and regional investment in data center capacity, while maintaining consistency with USDAnalytics market definitions and historical estimates.
Deliverables:
- Comprehensive Market Research Report (PDF and Excel) with detailed tables, charts, and interactive visualizations.
- Country-Specific Forecasts & Analysis.
- Segment-Wise Revenue Forecasts (2025–2034).
- Competitive Analysis, Benchmarking, and SWOT Profiles.
- Recent Developments & Innovation Tracker.
- Executive Summary & Analyst Commentary.
- Post-Purchase Analyst Support for Client-Specific Questions and Custom Data Requirements.
Table of Contents: Data Center Liquid Cooling Market, 2026–2034
1. Executive Summary
1.1. Global Data Center Liquid Cooling Market Highlights
1.2. Market Size and Growth Projections, 2026–2034
1.3. Key Industry Findings and Market Developments
1.4. Direct-to-Chip, Immersion and Spray Cooling Technology Outlook
1.5. Leading End-User Segments and Regional Demand
1.6. Competitive Landscape and Industry Structure
2. Data Center Liquid Cooling Market Overview (2026–2034)
2.1. Introduction to the Data Center Liquid Cooling Industry
2.2. Market Definition, Scope and Technology Coverage
2.3. Global Data Center Liquid Cooling Market Valuation and Forecast
- 2.3.1. Market Size in 2026: USD 7.6 Billion
- 2.3.2. Forecast Market Size in 2034: USD 39.1 Billion
- 2.3.3. Market Growth Rate: 22.8% CAGR
2.4. Data Center Liquid Cooling Industry Value Chain
2.5. Direct-to-Chip, Immersion and Hybrid Cooling Architectures
2.6. Cooling Infrastructure Components and System Integration
2.7. Key Market Insights and Commercial Demand Characteristics
3. Data Center Liquid Cooling Market Drivers, Trends and Opportunities
3.1. Key Market Drivers
- 3.1.1. AI GPU Rack Power Density Accelerates Direct-to-Chip Liquid Cooling Demand
- 3.1.2. Data Center Cooling Energy Costs and Total Cost of Ownership Influence Liquid Cooling Adoption
3.2. Emerging Technology and Industry Trends
- 3.2.1. Multi-Megawatt Coolant Distribution Units and Modular Liquid Cooling Infrastructure
- 3.2.2. Single-Phase and Two-Phase Liquid Cooling Technologies and Advanced Coolant Formulations
- 3.2.3. Selected 2026 Data Center Liquid Cooling Equipment Capacity Comparison
3.3. Emerging Market Opportunities
- 3.3.1. Brownfield Data Center Retrofits and Hybrid Air-Liquid Cooling Systems
- 3.3.2. Warm-Water Liquid Cooling and Data Center Waste Heat Recovery
3.4. Market Challenges and Commercial Constraints
- 3.4.1. Liquid Cooling Infrastructure Integration and Retrofit Costs
- 3.4.2. Coolant Compatibility, Leakage Management and Equipment Reliability
- 3.4.3. Component Qualification and Supplier Manufacturing Capacity
4. Data Center Liquid Cooling Market Recent Developments and Technical Framework
4.1. Recent Product Launches and Technology Commercialization (2024–2026)
4.2. Direct-to-Chip Cold Plates and Advanced Processor Cooling Developments
4.3. High-Capacity CDU Platforms and Modular Thermal Management
4.4. Manufacturing Expansion and Liquid Cooling Supply-Chain Developments
4.5. Industry Partnerships and Technology Collaborations
4.6. Acquisitions and Corporate Portfolio Developments
4.7. Coolant Chemistry, Dielectric Fluids and Monitoring Technologies
4.8. Regulatory and Technical Standards for Data Center Liquid Cooling Systems
- 4.8.1. European Union Data Center Energy Efficiency Reporting Requirements
- 4.8.2. ISO/IEC Power Usage Effectiveness and Water Usage Effectiveness Standards
- 4.8.3. ASHRAE Liquid Cooling Guidance and Thermal Operating Conditions
- 4.8.4. Open Compute Project Cold Plate, CDU and Coolant Specifications
5. Data Center Liquid Cooling Market Segmentation and Market Share Analysis
5.1. Global Market Size and Segment Revenue Outlook, 2026–2034
5.2. Data Center Liquid Cooling Market by Component
- 5.2.1. Solutions
- 5.2.1.1. Direct Liquid Cooling
- 5.2.1.2. Indirect Liquid Cooling
- 5.2.2. Services
- 5.2.2.1. Design and Consulting
- 5.2.2.2. Installation and Deployment
- 5.2.2.3. Support and Maintenance
5.3. Data Center Liquid Cooling Market by Type
- 5.3.1. Cold Plate Liquid Cooling
- 5.3.2. Immersion Liquid Cooling
- 5.3.3. Spray Liquid Cooling
5.4. Data Center Liquid Cooling Market by End-User
- 5.4.1. Cloud Providers
- 5.4.2. Colocation Providers
- 5.4.3. Enterprises
- 5.4.4. Hyperscale Data Centers
5.5. Market Share and Technology Adoption Analysis
- 5.5.1. Cold Plate Liquid Cooling Market Position
- 5.5.2. Immersion and Spray Liquid Cooling Market Outlook
- 5.5.3. Hyperscale Data Center Liquid Cooling Demand
- 5.5.4. Cloud and Colocation Liquid Cooling Deployment Trends
6. Data Center Liquid Cooling Market Country Analysis and Outlook
6.1. United States Data Center Liquid Cooling Market
- 6.1.1. Hyperscale AI Infrastructure and GPU Cooling Demand
- 6.1.2. Direct-to-Chip Cooling Manufacturing and Commercial Deployments
6.2. China Data Center Liquid Cooling Market
- 6.2.1. AI Computing Infrastructure and Cold-Plate Technology
- 6.2.2. Domestic Liquid Cooling Suppliers and Equipment Standardization
6.3. Germany Data Center Liquid Cooling Market
- 6.3.1. CDU Manufacturing and AI-Ready Colocation Infrastructure
- 6.3.2. Energy Efficiency Requirements and Heat Recovery Integration
6.4. Japan Data Center Liquid Cooling Market
- 6.4.1. Advanced AI Servers and Direct Liquid Cooling Deployment
- 6.4.2. Hybrid Cooling Systems and Facility Thermal Management
6.5. Singapore Data Center Liquid Cooling Market
- 6.5.1. High-Density Colocation and AI Data Center Expansion
- 6.5.2. Tropical Climate Cooling and Facility Energy Efficiency
6.6. India Data Center Liquid Cooling Market
- 6.6.1. AI Computing Infrastructure and Hyperscale Capacity Expansion
- 6.6.2. Domestic Liquid Cooling Equipment Manufacturing and Supply Chains
7. Data Center Liquid Cooling Market Size Outlook by Region (2026–2034)
7.1. North America Data Center Liquid Cooling Market Outlook
- 7.1.1. Market Size and Revenue Forecast by Component
- 7.1.2. Market Size and Revenue Forecast by Type
- 7.1.3. Market Size and Revenue Forecast by End-User
- 7.1.4. Country Outlook: United States, Canada and Mexico
7.2. Europe Data Center Liquid Cooling Market Outlook
- 7.2.1. Market Size and Revenue Forecast by Component
- 7.2.2. Market Size and Revenue Forecast by Type
- 7.2.3. Market Size and Revenue Forecast by End-User
- 7.2.4. Country Outlook: Germany, United Kingdom, France, Spain, Italy, Russia and Rest of Europe
7.3. Asia Pacific Data Center Liquid Cooling Market Outlook
- 7.3.1. Market Size and Revenue Forecast by Component
- 7.3.2. Market Size and Revenue Forecast by Type
- 7.3.3. Market Size and Revenue Forecast by End-User
- 7.3.4. Country Outlook: China, India, Japan, South Korea, Australia, Southeast Asia and Rest of Asia Pacific
7.4. South America Data Center Liquid Cooling Market Outlook
- 7.4.1. Market Size and Revenue Forecast by Component
- 7.4.2. Market Size and Revenue Forecast by Type
- 7.4.3. Market Size and Revenue Forecast by End-User
- 7.4.4. Country Outlook: Brazil, Argentina and Rest of South America
7.5. Middle East and Africa Data Center Liquid Cooling Market Outlook
- 7.5.1. Market Size and Revenue Forecast by Component
- 7.5.2. Market Size and Revenue Forecast by Type
- 7.5.3. Market Size and Revenue Forecast by End-User
- 7.5.4. Country Outlook: Saudi Arabia, United Arab Emirates, Rest of Middle East, South Africa, Egypt and Rest of Africa
8. Data Center Liquid Cooling Market Competitive Landscape and Leading Companies
8.1. Global Data Center Liquid Cooling Industry Competitive Structure
8.2. Integrated Thermal Management and Facility Cooling Suppliers
8.3. Direct-to-Chip Cooling, Cold Plate and CDU Manufacturers
8.4. Immersion Cooling and Advanced Dielectric Cooling Specialists
8.5. Competitive Benchmarking by Cooling Technology and Product Portfolio
8.6. Manufacturing Capabilities, System Integration and Service Coverage
8.7. Leading Data Center Liquid Cooling Companies
- 8.7.1. Vertiv Holdings Co.
- 8.7.2. Schneider Electric SE (Motivair)
- 8.7.3. Trane Technologies plc (LiquidStack)
- 8.7.4. CoolIT Systems Inc.
- 8.7.5. Boyd Corporation
- 8.7.6. Delta Electronics Inc.
- 8.7.7. DCX Liquid Cooling Systems
- 8.7.8. Daikin Industries Ltd. (Daikin Applied / Chilldyne)
- 8.7.9. STULZ GmbH
- 8.7.10. Rittal GmbH & Co. KG
- 8.7.11. Alfa Laval AB
- 8.7.12. Submer
- 8.7.13. Green Revolution Cooling (GRC)
- 8.7.14. Iceotope Technologies Ltd.
- 8.7.15. ZutaCore Inc.
8.8. Company Profiles and Comparative Analysis
- 8.8.1. Company Overview and Business Segments
- 8.8.2. Liquid Cooling Products and Technology Portfolio
- 8.8.3. Manufacturing and Regional Presence
- 8.8.4. Recent Product Launches, Partnerships and Acquisitions
- 8.8.5. Competitive Positioning and SWOT Profiles
9. Data Center Liquid Cooling Market Research Methodology
9.1. Research Scope and Market Definition
9.2. Primary and Secondary Research Framework
9.3. Market Size Estimation and Forecast Methodology
9.4. Supply-Side and Demand-Side Market Assessment
9.5. Market Segmentation and Revenue Allocation
9.6. Regional Market Analysis and Country Forecasting
9.7. Data Validation and Triangulation
9.8. Assumptions, Forecast Limitations and Market Boundaries
10. Appendix
10.1. Acronyms and Abbreviations
10.2. List of Tables
10.3. List of Figures
10.4. Market Segmentation Definitions
10.5. Research Assumptions and Data Notes
10.6. Related Data Center Infrastructure Market Research
