Market Overview: Nanofiltration Membranes Market Expands with Industrial Water Reuse, Selective Separation and Advanced Water Purification
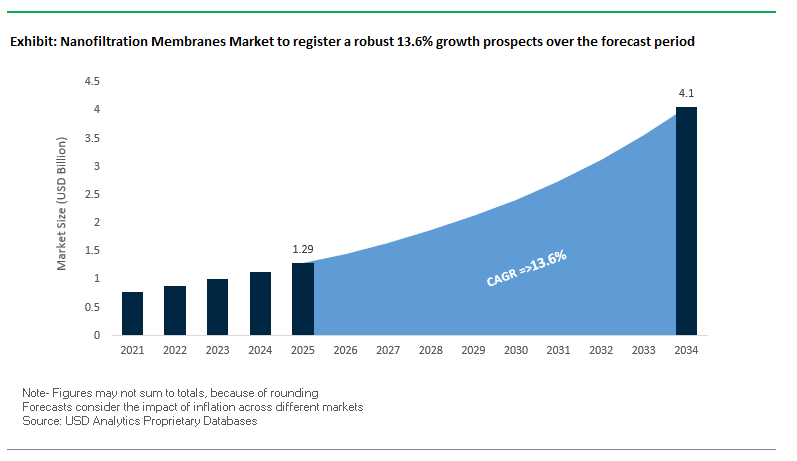
The global Nanofiltration Membranes Market is projected to increase from USD 1.29 billion in 2025 to USD 4.1 billion by 2034, registering a CAGR of 13.6% during the forecast period. Market growth is supported by industrial wastewater recycling, municipal drinking water treatment, selective ion separation and resource recovery applications. Nanofiltration (NF) membranes operate between ultrafiltration (UF) and reverse osmosis (RO), selectively retaining multivalent ions, larger dissolved organic molecules and certain contaminants while allowing varying degrees of monovalent salt passage. This separation capability supports water softening, sulfate removal, partial demineralization and advanced purification, with operating pressures generally lower than high-rejection RO in comparable applications where complete desalination is unnecessary.
Industrial water treatment and process separation represent major demand segments, particularly across chemicals, textiles, dairy processing, pharmaceuticals and mineral processing. Nanofiltration supports wastewater recovery, selective contaminant removal, whey concentration, partial mineral removal and lithium-brine purification. Municipal applications include drinking-water softening, natural organic matter reduction and treatment of selected emerging contaminants, including PFAS, where removal efficiency depends on membrane characteristics and operating conditions. Spiral-wound polymeric membranes remain widely deployed, while hollow-fiber, ceramic and tubular configurations serve applications with different fouling, chemical-resistance and pretreatment requirements. Commercial demand is influenced by membrane selectivity, energy consumption, cleaning frequency, replacement costs and concentrate management.
Asia Pacific represents an important regional market, supported by industrial wastewater treatment, manufacturing activity and municipal water purification across China, India, Japan and other economies. North America contributes demand from drinking-water treatment, industrial water reuse and emerging-contaminant management, while Europe maintains established applications in municipal water softening, dairy processing and industrial membrane separation. The Middle East and other water-stressed regions support demand for sulfate removal, selective water treatment and resource recovery. Competition includes membrane manufacturers, integrated water treatment companies and specialized separation technology providers, with differentiation centered on ion selectivity, membrane permeability, fouling resistance and lifecycle treatment economics.
Key Insights: Nanofiltration Membranes Market
Polymeric Membranes Dominate Material Demand: Polymeric nanofiltration membranes account for 85% of the market in 2025, supported by established thin-film composite technology, scalable manufacturing and widespread municipal and industrial applications.
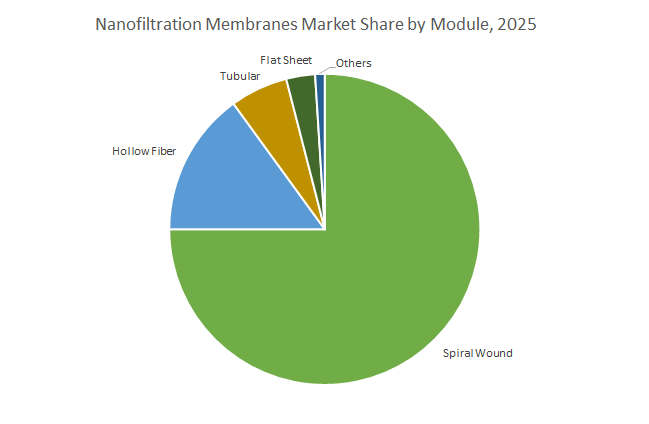
Spiral-Wound Membranes Lead Module Configuration: Spiral-wound elements hold 75% of market share in 2025, driven by applications in drinking-water purification, industrial wastewater treatment and food processing.
Industrial Applications Account for the Largest Share: Industrial applications represent 65% of the market in 2025, compared with 35% for municipal applications, supported by demand from chemicals, textiles, dairy processing, pharmaceuticals and mineral separation.
Selective Separation Supports Water Softening and Resource Recovery: Nanofiltration membranes enable hardness reduction, sulfate removal, partial demineralization and selective recovery of materials from lithium brines, dairy streams and industrial effluents.
Energy Efficiency and Membrane Fouling Influence Operating Costs: Feed pressure, membrane permeability, cleaning frequency, replacement costs and concentrate management shape filtration economics, with low-pressure and fouling-resistant membranes providing technological differentiation.
Hollow-Fiber and Specialty Membranes Expand Applications: Hollow-fiber nanofiltration, chemically resistant polymeric membranes and organic solvent nanofiltration technologies support municipal water reuse, challenging industrial wastewater treatment and chemical-process separation.
Recent Developments in Nanofiltration Membranes, Industrial Water Treatment and Selective Separation Technologies
Recent developments in the Nanofiltration Membranes Market reflect increasing commercialization of selective membrane materials, lower-energy drinking water treatment technologies and advanced industrial separation systems. In August 2026, Toray Industries announced the global introduction of two nanofiltration membrane element models, NE8040-XDM and NE8040-90F, which had been launched in July. The NE8040-XDM incorporates a chemically durable membrane design for industrial wastewater treatment, minimal-liquid-discharge (MLD) and zero-liquid-discharge (ZLD) applications, while the NE8040-90F targets advanced water purification, hardness removal and selected emerging contaminants, including PFAS. According to Toray's official water-treatment membrane announcements, the expanded portfolio reflects greater product specialization between industrial wastewater processing and lower-pressure municipal purification applications.
In March 2026, DuPont launched upgraded FilmTec NF270-400/34 nanofiltration elements for municipal drinking water treatment. The company reported that the upgraded membrane elements can achieve equivalent flux with 6–10% lower energy consumption and up to 30% lower initial pressure drop compared with earlier models under the stated comparison conditions. The DuPont FilmTec NF270-400/34 product announcement also identifies improved biofouling protection and membrane durability as product characteristics. The development reflects increasing emphasis on energy efficiency, hydraulic performance and maintenance requirements in municipal nanofiltration equipment.
Municipal water reuse projects are also extending commercial deployment of hollow-fiber nanofiltration. In July 2025, NX Filtration received a repeat order to double the capacity of a hollow-fiber nanofiltration installation serving the SAPAL water utility in León, Mexico. The project forms part of an indirect potable reuse system incorporating hollow-fiber NF and advanced oxidation technologies, with the two project phases providing a combined planned capacity of 34 million liters per day. The NX Filtration municipal water reuse expansion represents a commercial-scale application of hollow-fiber membrane separation in reclaimed municipal wastewater treatment.
Product development has also expanded into selective contaminant-removal applications. In May 2025, LG Chem, through LG Water Solutions, introduced the LG NF9 high-rejection nanofiltration membrane for municipal and industrial water treatment. The product is designed for removal of multivalent ions, natural organic matter and selected emerging contaminants, including PFAS and trihalomethanes. Its published specifications report a minimum salt rejection of 98.7% under defined magnesium sulfate test conditions. The development demonstrates increasing product differentiation around selective contaminant retention, low-pressure operation and membrane fouling resistance rather than complete desalination across all feedwater compositions.
Emerging Trends and Opportunities in the Nanofiltration Membranes Market
Growth in Selective Water Softening and Desalination Pre-treatment
One of the most prominent trends shaping the nanofiltration membranes industry is their adoption in municipal and industrial water treatment for softening and partial desalination. Unlike reverse osmosis, NF membranes selectively reject multivalent ions (e.g., calcium, magnesium) while allowing beneficial monovalent ions to pass.
A study by the Bhabha Atomic Research Centre (BARC) revealed that advanced charged NF membranes achieved a 97% rejection rate for sodium sulfate ($Na_2SO_4$) while maintaining only 20% rejection of sodium chloride ($NaCl$). This makes NF highly efficient for applications like brackish water treatment, where reducing hardness without stripping all minerals is essential. Importantly, NF operates at significantly lower energy costs than RO, which is accelerating adoption in cost-sensitive regions.
Expansion in the Food and Beverage Industry
The food & beverage sector is emerging as a key growth vertical for NF membranes. They are widely used for juice clarification, dairy product concentration, and beer filtration helping preserve product integrity while improving process sustainability.
For example, in September 2023, NX Filtration supplied hollow fiber NF membranes to a Carlsberg brewery in Denmark for beer filtration. This application underscores the industry’s pivot toward advanced separation technologies that avoid heat and chemicals, aligning with consumer demand for natural, minimally processed products.
Strategic Investments in Manufacturing and R&D
Global leaders in the nanofiltration membranes market are doubling down on R&D and large-scale manufacturing facilities to meet surging demand. In July 2021, NX Filtration announced a high-tech megafactory in the Netherlands to expand production capacity. Partnerships with firms such as Jacobs Engineering and Lantania highlight growing confidence in NF as the future of industrial water treatment and water reuse projects worldwide.
Application in Pharmaceutical and Chemical Separations
The pharmaceutical and chemical industries are increasingly adopting organic solvent nanofiltration (OSN) for catalyst recycling, solvent recovery, and API purification. Unlike distillation, NF enables energy savings, reduced solid waste, and scalability.
A recent review in ACS Publications highlighted that OSN could substantially reduce the carbon footprint of pharmaceutical manufacturing. With rising regulatory pressure on green chemistry and sustainable manufacturing, NF membranes are poised to become a cornerstone of high-value chemical separations.
Regulatory Framework and E-E-A-T: Drinking Water Quality, PFAS Requirements and Nanofiltration Membrane Validation
Regulatory requirements affecting nanofiltration membranes vary according to water source, intended application, contaminant characteristics and discharge conditions. In the European Union, the Drinking Water Directive (EU) 2020/2184 establishes a risk-based framework for drinking-water quality, including chemical parameters and emerging contaminants. Its PFAS provisions include a parametric value of 0.10 µg/L for the sum of 20 specified PFAS and 0.50 µg/L for PFAS Total, with the applicable monitoring framework and national implementation governing compliance. The relevant PFAS requirements became applicable on January 12, 2026.
In the United States, the Environmental Protection Agency established federal drinking-water maximum contaminant levels of 4.0 parts per trillion each for PFOA and PFOS under its April 2024 PFAS National Primary Drinking Water Regulation. On May 18, 2026, EPA announced a proposed PFOA and PFOS compliance extension rule, potentially allowing eligible systems additional time until 2031. A separate proposal concerns other regulated PFAS. These proposed changes remain distinct from currently effective requirements. Nanofiltration performance for individual PFAS varies with molecular characteristics, membrane selectivity and operating conditions; the technology does not guarantee uniform removal of all PFAS compounds.
The EU Water Reuse Regulation (EU) 2020/741, applicable since June 26, 2023, establishes minimum reclaimed-water quality, monitoring, permitting and risk-management requirements for treated urban wastewater used in agricultural irrigation. Its requirements do not automatically extend to all industrial or potable reuse applications.
For drinking-water-contact products, NSF/ANSI/CAN 61 establishes health-effects criteria for materials and components used in water systems. This standard addresses potential chemical migration from products rather than independently certifying membrane contaminant-removal performance. Nanofiltration evaluation involves validated solute rejection, membrane integrity, permeability, fouling behavior and compatibility with application-specific water-quality requirements.
Market Share Analysis of the Nanofiltration Membranes Market
Market Share by Type of Nanofiltration Membranes
Polymeric nanofiltration membranes will dominate the market in 2025, holding an estimated 85% share, thanks to their cost-effectiveness, manufacturing scalability, and proven performance in both municipal and industrial applications. Materials such as polyamide, cellulose acetate, and polysulfone remain the backbone of NF technology.
However, ceramic nanofiltration membranes (8%) are rapidly gaining ground due to their superior durability, thermal stability, and chemical resistance, making them indispensable in harsh industrial settings such as chemical processing and aggressive wastewater treatment.
Meanwhile, hybrid nanofiltration membranes (5%), incorporating inorganic nanoparticles like TiO2 into polymeric matrices, are emerging as the bridge between low-cost polymeric options and high-performance ceramics. The “Others” category (2%), including biomimetic and thin-film nanocomposites (TFN), represents the next wave of high-performance NF membranes currently in R&D.
Market Share by Module Configuration
In terms of module design, spiral wound NF membranes (75%) dominate due to their high packing density, compact footprint, and cost-effectiveness, making them the industry standard for municipal water treatment and desalination pre-treatment.
Hollow fiber modules (15%) are gaining traction in wastewater treatment and industrial processes where resistance to fouling is critical. Tubular NF membranes (6%) serve niche markets with high-solid, viscous, or aggressive process streams, such as pulp & paper or textiles, where ease of cleaning is vital. Flat sheet membranes (3%) remain largely restricted to pilot-scale testing and R&D, while other niche formats (1%) serve highly specialized applications.
Market Share by Application Sector
Industrial applications (65%) account for the majority of the NF membranes market, with broad adoption across food & beverage, pharmaceuticals, textiles, mining, and chemicals. NF plays a crucial role in processes like whey demineralization, dye recovery, catalyst recycling, and selective metal removal, making it indispensable for resource recovery and sustainable manufacturing.
Meanwhile, municipal applications (35%) are steadily expanding, fueled by rising urban water demand, stricter water quality standards, and the need for potable reuse. NF is widely deployed in water softening, natural organic matter (NOM) removal, disinfection byproduct control, and micropollutant removal, as well as advanced wastewater recycling projects for direct and indirect potable reuse.
China: Regulatory Push and Industrial Investment Driving Nanofiltration
China’s nanofiltration membranes market is driven by strong government regulations and industrial expansion. The "Guiding Opinions on Promoting the Utilization of Wastewater Resources" sets a target to achieve a recycled water utilization rate of 25% or more in water-scarce cities by 2025, highlighting nanofiltration’s importance in water reuse applications. Major investments include the 2018 agreement between Sinochem International and Ningbo Xiangshan County for a RMB 3.5 billion production and R&D center, initially focused on reverse osmosis membranes with plans to expand into high-performance nanofiltration. Technological advancements such as the 2024 hollow-fiber ultrafiltration (UF) membrane with enhanced antifouling properties are increasingly integrated into multi-stage systems with nanofiltration for producing high-quality water. Key applications include seawater desalination and ultrapure water preparation for electronics and high-tech industries.
United States: Government-Funded Innovation and Advanced Manufacturing
The U.S. nanofiltration membranes market benefits from substantial government funding and academic research. The Department of Energy (DOE) and the National Alliance for Water Innovation (NAWI) selected 12 projects to enhance desalination and water reuse efficiency, including electrospray printing technology to fabricate porous membranes for improved filtration performance. NSF-supported research drives innovation in water purification, chemical separations, and biopharmaceutical applications, complementing federal initiatives. Corporate leaders such as DuPont Water Solutions are developing nanofiltration membranes to address emerging contaminants like PFAS, aligning with U.S. infrastructure modernization under the Bipartisan Infrastructure Law.
India: Rural Water Initiatives and Nanomaterial Integration
India’s nanofiltration membranes market is expanding through government programs and technological adoption. The “Jal Jeevan Mission” and the Department of Science & Technology’s Water Technology Initiative promote advanced filtration technologies in rural areas. In 2025, researchers highlighted the integration of nanomaterials graphene oxide, carbon nanotubes, and metal-organic frameworks (MOFs) into nanofiltration membranes, enhancing mechanical strength, permeability, and antifouling properties. Infrastructure investments, such as the Ghaziabad Nagar Nigam’s ₹150 crore Certified Green Municipal Bond for a Tertiary Sewage Treatment Plant (TSTP), underscore the commitment to advanced wastewater reuse, industrial water applications, and sustainable water management.
Germany: Industrial Leadership and Advanced Nanofiltration Solutions
Germany remains a leader in industrial nanofiltration applications, driven by environmental sustainability and regulatory compliance. Companies like PWT Wassertechnik specialize in nanofiltration to treat and reuse industrial wastewater efficiently. Technological innovations from MANN+HUMMEL focus on digital integration and membrane solutions to optimize industrial processes and support green energy initiatives. A 2025 market report noted Germany’s nanofiltration membranes market holds the largest market share in Europe, reflecting the country’s robust adoption of advanced water treatment systems and commitment to environmental sustainability.
Japan: Academic Excellence and Global Technology Provider
Japan’s nanofiltration membranes market is propelled by advanced research and international projects. The Membrane Engineering Group at Kobe University continues to develop novel functional membranes for water and atmospheric applications, advancing filtration performance. Toray Industries’ high-performance RO membranes for large-scale desalination plants in Saudi Arabia highlight Japan’s global role as a provider of cutting-edge membrane technologies, where nanofiltration is often employed as a critical stage for water purification.
Australia: Water Recycling Leadership and Research-Driven Advancements
Australia faces severe water scarcity, making water recycling and reuse a national priority. The government’s National Water Grid Fund invests in projects incorporating advanced nanofiltration and treatment plants. Academic research at the Institute for Sustainable Industries and Liveable Cities (ISILC) at Victoria University focuses on improving desalination recovery rates and reducing membrane fouling and scaling, addressing key technical challenges in nanofiltration systems. These initiatives enhance Australia’s capabilities in sustainable water management and advanced membrane technologies.
Competitive Landscape: Global Nanofiltration Membranes Market
The global Nanofiltration Membranes Market competitive landscape includes polymeric membrane manufacturers, specialized filtration technology companies, municipal water treatment providers and industrial separation suppliers. DuPont de Nemours, Inc. participates through FilmTec nanofiltration membranes, including NF270 drinking-water elements and LiNE-XD membranes for selective lithium-brine purification. Toray Industries, Inc. supplies nanofiltration elements for industrial wastewater treatment, hardness removal and advanced purification, including its NE8040 series. Nitto Denko Corporation, through Hydranautics, competes through ESNA, NANO-SW and HYDRACoRe membrane technologies for water softening, sulfate removal and natural organic matter reduction. LG Chem Ltd., through LG Water Solutions, participates through its LG NF9 membrane portfolio for selective municipal and industrial water treatment.
Specialized membrane manufacturers compete through module architecture, contaminant selectivity and application-specific operating performance. NX Filtration supplies hollow-fiber direct nanofiltration technology used in municipal water reuse, drinking-water purification and industrial wastewater treatment. Pentair plc, through X-Flow, participates through HFW1000 chlorine-tolerant hollow-fiber nanofiltration membranes and HFNano treatment configurations. Kovalus Separation Solutions, formerly Koch Separation Solutions, supplies FLUID SYSTEMS nanofiltration elements for hardness removal and natural organic matter treatment. MANN+HUMMEL participates through TRISEP and NADIR membrane technologies, including polymeric NF products used in water purification and industrial process separation.
Integrated water treatment providers maintain positions across municipal drinking water, contaminant removal and wastewater reuse. Veolia provides engineered nanofiltration treatment systems, including OPAMEM NANO and membrane-based sulfate removal technologies used in industrial water management. SUEZ operates independently and supplies membrane-based treatment capabilities for drinking-water softening, micropollutant control and industrial water purification. Its nanofiltration applications include Softazur M treatment configurations and integration with other water purification technologies. Both companies participate primarily through treatment-process engineering, equipment integration and operational services rather than competing exclusively as standalone membrane-material manufacturers.
Food, dairy and biotechnology processing represent an established competitive segment for industrial nanofiltration technologies. Alfa Laval supplies nanofiltration flat-sheet and spiral-wound membranes for dairy processing, whey demineralization and biotechnology applications. GEA Group provides integrated membrane filtration systems incorporating NF, UF and RO processes for dairy ingredients, food processing and industrial separation. Synder Filtration manufactures NFS, NFX, NFW and NFG nanofiltration membranes for lactose concentration, whey processing, selective salt removal and industrial wastewater applications, with differentiated membrane molecular-weight cutoffs and rejection characteristics.
Additional competition comes from specialized molecular separation and membrane-material suppliers. Evonik Industries AG supplies PuraMem organic solvent nanofiltration membranes for catalyst recovery, solvent recycling and chemical-process purification, representing a specialized nonaqueous application segment. JSC RM Nanotech, through its Membranium brand, manufactures spiral-wound nanofiltration elements for brackish-water softening, water clarification and industrial liquid separation. Competition across the wider industry reflects membrane permeability, ion selectivity, fouling resistance, operating-pressure characteristics, product qualification, system integration capabilities and lifecycle filtration costs.
Nanofiltration Membranes Market Report Scope
Nanofiltration Membranes Market
Parameter
Details
Market Size (2025)
$1.29 Billion
Market Size (2034)
$4.1 Billion
Market Growth Rate
13.6%
Segments
By Type (Polymeric, Ceramic, Hybrid, Others), By Module (Spiral wound, Tubular, Hollow Fiber, Flat sheet, Others), By Application (Municipal, Industrial)
Study Period
2020- 2025 and 2026-2034
Units
Revenue (USD)
Qualitative Analysis
Porter’s Five Forces, SWOT Profile, Market Share, Scenario Forecasts, Market Ecosystem, Company Ranking, Market Dynamics, Industry Benchmarking
Companies
DuPont de Nemours, Inc., SUEZ, Veolia, Toray Industries, Inc., Pentair plc, Asahi Kasei Corporation, The Dow Chemical Company, NX Filtration, Kubota Corporation, LG Chem, MANN+HUMMEL, Evoqua Water Technologies, Koch Industries, Hydranautics (a Nitto Group Company), V.A. TECH WABAG Ltd.
Countries
US, Canada, Mexico, Germany, France, Spain, Italy, UK, Russia, China, India, Japan, South Korea, Australia, South East Asia, Brazil, Argentina, Middle East, Africa
Nanofiltration Membranes Market Segmentation
By Type
Polymeric
Ceramic
Hybrid
Others
By Module
Spiral wound
Tubular
Hollow Fiber
Flat sheet
Others
By Application
Municipal
Industrial
Countries Analyzed
North America (US, Canada, Mexico)
Europe (Germany, UK, France, Spain, Italy, Russia, Rest of Europe)
Asia Pacific (China, India, Japan, South Korea, Australia, South East Asia, Rest of Asia)
South America (Brazil, Argentina, Rest of South America)
Middle East and Africa (Saudi Arabia, UAE, Rest of Middle East, South Africa, Egypt, Rest of Africa)
Leading Companies in the Nanofiltration Membranes Market
This report investigates the fast-rising nanofiltration membranes market, delivering analysis reviews on how selective separations, resource recovery, and energy efficiency are propelling NF from niche to mainstream across municipal and industrial plants. It highlights breakthroughs in thin-film chemistries, direct-NF hollow fiber designs, and digitally modeled RO–NF–EDI trains that sharpen multivalent ion rejection while cutting pressure and OPEX. The study further highlights consolidation moves, project wins, and application pivots (softening, PFAS/NOM control, lithium brines, OSN in chemicals) that are reshaping vendor strategies and qualification criteria. By converting performance metrics (permeance, selectivity, fouling resistance) into lifecycle economics and procurement scorecards, USDAnalytics equips decision-makers with bankable evidence this report is an essential resource for utilities, EPCs, and plant owners standardizing NF in reuse, pre-treatment, and high-value process lines. Scope Includes-
Segmentation: By Type (Polymeric, Ceramic, Hybrid, Others); By Module (Spiral Wound, Tubular, Hollow Fiber; Flat Sheet; Others); By Application (Municipal, Industrial)
Geographic Scope: Analysis spans 25+ countries across North America, Europe, Asia Pacific, Latin America, the Middle East & Africa.
Time Frame: Historic 2021–2024; Forecast 2025–2034.
Companies: Analysis/profiles of 15+ companies.
Research Methodology
USDAnalytics evaluates the global Nanofiltration Membranes Market using a combined top-down and bottom-up market-sizing framework covering polymeric, ceramic, hybrid and other membrane materials; spiral-wound, hollow-fiber, tubular and flat-sheet configurations; and municipal and industrial applications. The research incorporates primary industry interviews with membrane manufacturers, water treatment operators, original equipment manufacturers, engineering contractors and process-separation specialists, supplemented by company disclosures, product specifications, technical publications, regulatory databases and project information.
Market estimates are triangulated using membrane equipment demand, industrial water treatment activity, municipal purification infrastructure, filtration-module consumption, installed capacity and membrane replacement requirements. Technical and commercial assessments examine permeability, selective ion rejection, membrane fouling, transmembrane pressure, cleaning frequency, recovery efficiency and lifecycle treatment costs. The 2025–2034 forecast incorporates industrial wastewater recycling, municipal drinking-water treatment, dairy and chemical processing applications, resource recovery activity, membrane technology adoption and evolving regulatory requirements, with competitive benchmarking covering supplier portfolios, application coverage and membrane performance characteristics.
Deliverables:
Comprehensive Market Research Report (PDF and Excel) with detailed tables, charts, and interactive visualizations.
Country-Specific Forecasts & Analysis.
Segment-Wise Revenue Forecasts (2025–2034).
Competitive Analysis, Benchmarking, and SWOT Profiles.
Recent Developments & Innovation Tracker.
Executive Summary & Analyst Commentary.
Post-Purchase Analyst Support for Client-Specific Questions and Custom Data Requirements.
Table of Contents: Nanofiltration Membranes Market
1. Executive Summary
1.1. Market Highlights
1.2. Key Insights for Stakeholders
1.3. Global Market Snapshot
2. Nanofiltration Membranes Market Outlook (2025–2034)
2.1. Introduction: Strong Market Growth and Industry Transformation
2.2. Market Valuation and Growth Projections (2025–2034)
NF shines when you need selective removal e.g., hardness, color, NOM, and divalent salts while retaining beneficial monovalent ions and operating at lower pressures than RO. That translates to smaller pumps, reduced energy, and simpler brine management for softening, pre-treatment, and partial desalination.
Spiral wound dominates for compact skids, high packing density, and cost efficiency in municipal and general industrial duty. Hollow fiber is attractive where fouling resilience, backwashability, or simplified pretreatment matters (e.g., challenging reuse feeds); it can stabilize SDI and push higher uptime between cleanings.
NF enables ion-specific separations: concentrating divalent salts/lactose or rejecting sulfate while passing monovalent ions/solvents. In lithium brines, targeted rejection lifts yield before polishing; in dairy and specialty chemicals, NF reduces steam use vs. evaporation and improves product quality while shrinking footprint.
Pilot with your actual feed to map flux decline and set conservative LMH/TMP, then integrate upstream MF/UF or media for colloids, optimize antiscalant/alkalinity control, and deploy condition-based monitoring (ΔP, normalized flux). A validated cleaning window (CIP chemistry, temperature, duration) locks in lifecycle cost.
Prioritize divalent rejection at design flux, permeability (LMH/bar), organic/NOM and color removal, guaranteed SDI at downstream interface, CIP recovery, membrane life, and verified performance on target contaminants (e.g., PFAS surrogates). Roll these into a total cost per 1,000 m³ model for apples-to-apples evaluation.