Parenteral Products Packaging Market to Surge from $29.2 Billion in 2025 to $69.4 Billion by 2034 at 10.1% CAGR Driven by Biologics and Patient-Centric Delivery Systems
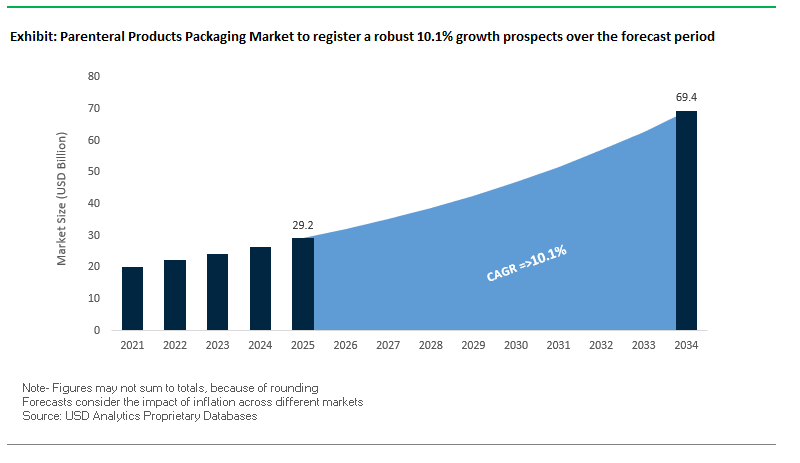
The global Parenteral Products Packaging Market is projected to increase from USD 29.2 billion in 2025 to USD 69.4 billion by 2034, expanding at a CAGR of 10.1%. The market covers primary packaging and associated delivery-system components used for sterile drug products administered by injection or infusion, including vials, prefilled syringes, cartridges, ampoules, bags and bottles, ready-to-use containers, elastomeric stoppers, plungers and seals. Packaging performance is closely connected with drug stability because parenteral formulations bypass many of the body's natural barriers and therefore require tightly controlled sterility, container-closure integrity, material compatibility and functional performance throughout manufacturing, storage and administration.
Vials account for approximately 35% of product-type demand, reflecting their continued use across vaccine packaging applications, small-molecule injectables, biologics and lyophilized products, while prefilled syringes represent approximately 30% and are increasingly integrated with safety systems and autoinjectors. Glass remains central across rigid pharmaceutical packaging formats such as vials, ampoules, cartridges and syringes because of its chemical resistance and barrier properties, while cyclic olefin polymers and other engineered materials are used where break resistance, low ion release, low silicone exposure or specialized storage conditions are important. Elastomeric stoppers and plungers are equally critical because they form part of the functional container-closure system rather than operating as independent accessories. USP General Chapter <382>, effective from December 2025, specifically addresses functional suitability of elastomeric components within parenteral packaging and delivery systems.
Biologics, biosimilars, GLP-1 therapies and other high-value injectable products are increasing demand for tighter dimensional tolerances, controlled siliconization, lower extractables and leachables, improved glass surface performance and integrated container-component qualification. At the same time, pharmaceutical manufacturers are increasing adoption of ready-to-use and ready-to-fill vials, syringes and cartridges supplied prewashed and sterilized in standardized nest-and-tub configurations. These formats reduce container preparation steps at aseptic fill-finish sites and support highly automated processing of smaller and more diverse product batches. Current capacity investments by SCHOTT Pharma, Stevanato Group and BD show that RTU containers and high-performance prefillable systems are moving further into commercial-scale manufacturing.
The market is also becoming more closely connected with drug-delivery-device design. Large-volume subcutaneous biologics are driving development of 2.25 mL, 3 mL, 5 mL and larger syringe and cartridge platforms, while pen injectors and autoinjectors increasingly require primary containers to meet precise dimensional, break-loose, glide-force, needle, plunger and closure specifications.
Key Insights for Industry Professionals
The Parenteral Products Packaging Market is valued at USD 29.2 billion in 2025 and is projected to reach USD 69.4 billion by 2034 at a CAGR of 10.1%.
Vials account for approximately 35% of product-type demand, supported by broad use across liquid and lyophilized injectables, vaccines, biologics and small-molecule formulations. Prefilled syringes represent approximately 30%, with increasing integration into self-administration and combination-product platforms.
Pharmaceutical and biotechnology companies represent approximately 65% of application demand, reflecting the importance of packaging selection during formulation development, stability testing, fill-finish and commercial-scale manufacturing.
Ready-to-use vials, syringes and cartridges are expanding across aseptic fill-finish, with manufacturers increasing standardized nest-and-tub capacity and high-speed RTU production for biologics and other complex injectables.
Container-closure performance is increasingly evaluated as a complete system. USP <382> addresses functional suitability of elastomeric components within parenteral packaging/delivery systems, while FDA's August 2026 draft Container Closure Systems guidance addresses quality evaluation of complete CCSs for drugs and biological products.
Large-volume and high-viscosity biologics are expanding primary-container requirements. Current 5–5.5 mL cartridge and PFS programs from SCHOTT Pharma and BD demonstrate closer engineering between primary containers and autoinjector platforms.
Recent Developments Highlight Strategic Investments and Sustainability Focus in Parenteral Packaging
West Commercializes Integrated Synchrony S1 Prefillable Syringe System
In January 2026, West Pharmaceutical Services announced global commercial availability of its Synchrony S1 Prefillable Syringe System, following its initial launch at CPHI in October 2025. The platform combines syringe barrel, plunger and needle-shield or tip-cap configurations as an integrated system rather than requiring pharmaceutical developers to qualify each primary-container component independently. Initial configurations include 1 mL long and 2.25 mL staked-needle systems for biologics, together with 1 mL vaccine configurations and West's NovaPure and FluroTec barrier-film plungers. The development reflects increasing movement toward pre-engineered container-closure systems with component-level performance data for biologics and combination products.
BD Invests $110 Million in U.S. Prefillable Syringe Manufacturing for Biologics and GLP-1 Drugs
In January 2026, BD announced a USD 110 million investment to introduce BD Neopak glass prefillable syringe manufacturing at its Columbus, Nebraska site. The investment expands domestic capacity for 1 mL and 2.25 mL Neopak syringes used with biologics and combination products and is expected to create approximately 120 jobs. BD specifically linked the investment to increasing demand from biologic and GLP-1 drug programs requiring high-viscosity compatibility and integration with self-injection devices.
Later that month, BD and Ypsomed expanded their collaboration to develop a 5.5 mL BD Neopak XtraFlow glass prefillable syringe compatible with the YpsoMate 5.5 autoinjector. The development uses an 8 mm needle and thin-wall cannula architecture to address higher-volume and higher-viscosity subcutaneous delivery, with feasibility samples scheduled during 2026. The program demonstrates how parenteral primary-container development is increasingly being coordinated with device-platform dimensions and injection performance.
SCHOTT Pharma Introduces cartriQ BioPure for Sensitive Biologics
In April 2026, SCHOTT Pharma announced cartriQ BioPure, a sterile ready-to-use glass cartridge designed for sensitive biologics. The cartridge is manufactured from enhanced FIOLAX Pro glass tubing and incorporates tighter controls on sodium and aluminum release, an improved extractables-and-leachables profile and baked-on silicone technology intended to reduce drug-container interaction. Coated elastomeric plunger stoppers and combi-seals are integrated into the system. SCHOTT Pharma plans commercial introduction at the end of 2026, with development samples already available.
The platform expands SCHOTT Pharma's BioPure architecture across vials, syringes and cartridges, illustrating the industry's movement toward differentiated primary-container families for sensitive biologics rather than relying on one standard glass configuration across all injectable formulations.
SCHOTT Pharma Adds More Than $60 Million of U.S. Vial Capacity
In June 2026, SCHOTT Pharma inaugurated expanded pharmaceutical-vial production at its Lebanon, Pennsylvania facility following an investment of more than USD 60 million. The expansion adds capacity for both conventional and sterile ready-to-use glass vials intended for biologics, complex injectable therapies, vaccines and emergency medicines. The investment was supported by the U.S. Biomedical Advanced Research and Development Authority and adds automated production capabilities for high-value vial formats.
The project is particularly relevant to the parenteral market because it combines regional supply-chain localization with RTU container expansion. Rather than increasing only bulk-vial capacity, manufacturers are increasingly investing in preprocessed containers that can enter aseptic fill-finish operations with fewer preparation stages.
Stevanato Group Advances U.S. RTU Vial and European Syringe and Cartridge Capacity
Stevanato Group's 2026 capacity program is expanding several high-value parenteral container formats simultaneously. During the second quarter, the company completed initial performance qualification of its first EZ-fill vial line at Fishers, Indiana and prepared the line for customer validations. Its Latina, Italy site continued ramping high-value prefillable syringe capacity while preparing installation of next-generation RTU 400 EZ-fill cartridge lines, with commercial production expected in early 2027.
The company's disclosures also indicate growing demand across traditional 1.5 mL and 3 mL cartridges and larger-volume formats, supported by biologics and the shift of selected therapies from intravenous toward subcutaneous administration. These investments reinforce RTU processing as a major competitive capability across vials, syringes and cartridges rather than a niche format limited to prefilled syringes.
In July 2026, Aptar Pharma launched an integrated system-level framework for injectable drug-delivery systems, combining partner components with performance testing and data packages intended to support earlier container-system decisions. The framework addresses areas including sealing performance, component interaction and system-level testing as pharmaceutical developers adapt to the functional-suitability expectations of USP <382>.
The approach was extended in September 2026 through work with Stevanato Group, evaluating complete prefilled-syringe configurations comprising the syringe, plunger and rigid needle shield under a USP <382>-aligned methodology. This is significant for the packaging market because functional qualification is increasingly moving from individual stopper or syringe specifications toward evaluation of the assembled delivery system.
SGD Pharma Expands Tubular Vial, Ampoule and RTU Capabilities Through Alphial Acquisition
In August 2025, SGD Pharma announced an agreement to acquire Alphial S.r.l., an Italian manufacturer of tubular glass vials, ampoules and ready-to-use products operating four manufacturing sites. SGD subsequently incorporated the acquired capabilities into its broader molded and tubular pharmaceutical-glass portfolio.
The acquisition expands SGD Pharma beyond its traditional molded-glass strength and provides a larger European platform for tubular parenteral formats. Combined molded and tubular capabilities enable the company to address conventional injection vials, ampoules and more specialized RTU requirements across different filling volumes and pharmaceutical applications.
Large-Volume Cartridge Platforms Link Primary Packaging More Closely with Injection Devices
Primary-container suppliers are also expanding beyond conventional 1–3 mL device formats. SCHOTT Pharma's TOPPAC RTU polymer cartridge was prevalidated in January 2026 for compatibility with SHL Medical's Maggie large-volume autoinjector platform, following development of a 5 mL glass cartridge configuration. The polymer cartridge uses COC and standardized RTU nest-and-tub processing and is intended for sensitive biologics where break resistance, low silicone exposure or specialized storage conditions can influence material selection.
In July 2026, SCHOTT Pharma and Nemera also verified the company's 3 mL cartriQ RTU glass cartridge with Nemera's pen-injector platform. Together with BD's 5.5 mL PFS program, these developments show primary packaging increasingly being engineered around injection-device interfaces before commercial drug launch rather than selected independently at a later development stage.
Trends and Opportunities Transforming the Parenteral Products Packaging Market
Strategic Onshoring of Glass Packaging Manufacturing for Supply Chain Resilience
The parenteral products packaging market is experiencing a strategic reconfiguration as pharmaceutical packaging manufacturers pursue onshoring to strengthen supply chain resilience. The vulnerabilities exposed during the COVID-19 pandemic—when global shortages of vials and syringes delayed critical vaccine distribution—highlighted the risks of dependence on overseas production hubs. In response, leading glass packaging companies are bringing production closer to pharmaceutical markets in the U.S. and Europe. A global specialty glass manufacturer invested over EUR 40 million in a new melting tank for pharmaceutical tubing, while in late 2024, plans were announced for a new tubing facility in the United States. These investments represent a significant capacity build-out designed to guarantee steady supply.
Beyond mitigating geopolitical and logistical risks such as shipping delays, tariffs, and trade disputes, onshoring initiatives are directly linked to tighter quality control. Borosilicate glass, the gold standard for injectable packaging, requires precision manufacturing to meet the exacting standards of regulatory agencies and biopharma customers. By locating production near end-users, manufacturers enable faster feedback loops, closer collaboration with pharma companies, and improved responsiveness to product customization. This trend reflects a permanent shift toward regionalizing pharmaceutical glass production to reduce risk, enhance quality, and strengthen long-term supply security.
Accelerated Adoption of Ready-to-Use Systems and Integrated Delivery Devices
Another defining trend in the parenteral packaging sector is the accelerated transition from traditional vial-syringe formats to ready-to-use (RTU) systems such as pre-filled syringes (PFS), auto-injectors, and integrated delivery platforms. In the last decade, pre-filled syringes have accounted for a growing proportion of approvals for injectable drugs in the U.S. and Europe, particularly in biologics and specialty therapies. This shift reflects the demand for precise dosing, improved safety, and enhanced patient convenience.
The rise of patient-centric care models is amplifying adoption of devices such as auto-injectors, which allow patients to self-administer treatments for chronic conditions at home. A major medical device manufacturer demonstrated this trend in September 2021 with the launch of an auto-injector platform capable of accommodating both 1mL and 2.25mL syringes, underscoring the industry’s focus on flexibility and usability. These innovations reduce dosing errors, needle-stick injuries, and hospital visits, thereby improving adherence and patient outcomes. As biologics and biosimilars dominate the pharmaceutical pipeline, RTU systems and integrated delivery solutions are becoming indispensable, reshaping the competitive landscape of parenteral packaging.
Development of Novel Containment Solutions for High-Potency APIs (HPAPIs)
The rising pipeline of highly potent active pharmaceutical ingredients (HPAPIs), particularly in oncology, presents a critical opportunity for innovation in containment packaging. HPAPIs with Occupational Exposure Bands (OEB) of 4 and 5 require packaging solutions that protect both operators and patients at microgram exposure levels. Contract development and manufacturing organizations (CDMOs) are leading the charge by designing specialized containment systems tailored for HPAPIs. These solutions ensure safety in handling, storage, and transport while preventing cross-contamination in production facilities.
Simultaneously, there is rising demand for specialized glass vials and cartridges that provide superior barrier protection for high-value drugs. Innovations include customized containers engineered to minimize drug-container interaction and resist oxygen, light, and moisture penetration. For instance, in March 2022, a leading pharmaceutical glass company launched a 100mL vial specifically designed for oncology applications, reinforcing the market opportunity for bespoke, high-performance containment solutions. As the prevalence of oncology therapies and advanced biologics grows, the development of HPAPI-compatible packaging will become a key driver of competitive differentiation.
Innovation in Materials and Connectivity for At-Home Drug Administration
The rise of at-home care and digital health is opening new frontiers in parenteral packaging. One of the most promising opportunities lies in the integration of connectivity into injection systems. Smart injectors equipped with Bluetooth-enabled plunger rods can transmit dosage and administration data to healthcare providers in real time, enabling remote monitoring and compliance tracking without altering the drug container. This creates a clear, scalable pathway for pharma companies to add value to existing injectable portfolios by embedding connectivity without regulatory revalidation of the primary container.
Wearable drug delivery platforms represent another high-growth opportunity. Designed to deliver large volumes of medication subcutaneously, these discreet, hands-free devices are transforming patient experience by replacing frequent IV infusions with home-based therapies. A medical technology firm has already introduced a wearable system that automates drug transfer from pre-filled vials and delivers it over a programmed period. This innovation not only improves patient convenience but also reduces hospital resource burdens, aligning with healthcare system priorities to expand outpatient and home-based care. As demand for biologics and specialty injectables rises, innovations in smart, connected, and wearable delivery platforms will play a central role in the future of parenteral packaging.
Competitive Landscape: Primary Containers, Elastomeric Components and Integrated Injectable Systems Define Competition
Competition in the Parenteral Products Packaging Market is distributed across pharmaceutical-glass manufacturers, prefillable syringe and cartridge suppliers, elastomeric-component specialists and integrated drug-delivery companies. SCHOTT Pharma, Stevanato Group, Gerresheimer, Nipro PharmaPackaging, SGD Pharma and Becton, Dickinson and Company represent major suppliers of vials, syringes, cartridges and ampoules. SCHOTT Pharma competes across glass and COC syringes, RTU vials and glass and polymer cartridges; Stevanato Group combines EZ-fill RTU containers with prefillable syringes and drug-delivery capabilities; Nipro PharmaPackaging operates from glass tubing through finished D2F prefillable syringes, RTU vials, cartridges and ampoules. Gerresheimer's portfolio similarly spans glass and polymer syringes, vials, cartridges and ampoules, while its December 2024 acquisition of Bormioli Pharma added further European primary-packaging and closure capabilities.
A second competitive group centers on elastomeric closures and assembled container systems. West Pharmaceutical Services, Aptar Pharma and Datwyler compete through vial stoppers, syringe plungers, coated elastomers, needle shields and other components that directly influence container-closure integrity, extractables and leachables, particle generation and administration performance. West's Synchrony S1 illustrates the movement toward verified multi-component PFS systems, while Aptar's 2026 framework addresses complete injectable-system evaluation. Datwyler has expanded high-performance plunger programs for prefilled syringes, cartridges and GLP-1 applications, including FirstLine and coated NeoFlex platforms. With USP <382> now emphasizing functional suitability within the complete packaging/delivery system, dimensional compatibility, sealing, penetration force, self-sealing behavior, plunger functionality and component interaction are becoming increasingly important competitive parameters.
Competition is therefore shifting beyond basic container supply toward system compatibility, ready-to-use processing, biologic stability, extractables and leachables control, low-particle performance, container-closure integrity, fill-finish automation and device integration. The FDA's August 2026 draft Container Closure Systems guidance similarly treats container-closure evaluation as a drug-quality function and includes systems that also serve as device constituent parts of combination products. Companies with standardized RTU platforms, high-speed nest-and-tub formats and verified interfaces with autoinjectors and pen systems are competing alongside traditional vial and ampoule suppliers, while regional investments in the United States and Europe are increasing competition around supply continuity and local pharmaceutical manufacturing capacity.
Vials lead Market Share by Product Type in Parenteral Packaging, while Pre-filled Syringes scale fastest
Vials retain the largest product-type share at 35% of parenteral packaging because they are the most versatile, validated, and automation-ready primary container for small molecules, biologics, and lyophilized drugs; their compatibility with diverse stopper/seal systems and proven stability files lowers regulatory risk and speeds fill-finish scalability. Pre-filled syringes (30%) are the structural growth engine as self-administration and patient-centric drug delivery accelerate—silicone-oil-free barrels, sensitive-biologic plungers, and integrated safety needles reduce medication errors and needlestick incidents while meeting stringent extractables/leachables controls. Bags & bottles sustain a durable share in large-volume parenterals (LVPs) as hospitals standardize on non-PVC, multi-layer films to enhance drug compatibility and reduce plasticizer migration. Cartridges expand with the proliferation of auto-injectors and pen systems in diabetes and chronic care, locking packaging selection to device platform strategy. Ampoules persist as a niche for single-dose, highly sensitive actives where rubber contact is undesirable, despite handling and particulate concerns. Finally, ready-to-use (RTU) systems—fully sterilized primary containers and drug-device combinations—capture premium, fast-growing share by compressing preparation time and error risk in critical-care settings. The product mix underscores how biologics, home care, and sterility assurance are realigning market share away from commodity containers to high-value, compliance-forward formats.
Pharmaceutical & Biotech hold dominant Market Share by Application in Parenteral Packaging
Pharmaceutical and biotechnology companies account for 65% of demand because parenteral packaging decisions are made at the aseptic fill-finish node, where stability, sterility assurance, and regulatory compliance dictate container closure selection across clinical and commercial scales. Sponsors’ pivot to biologics and biosimilars concentrates spend on pre-filled syringes, advanced vial systems, and RTU platforms that minimize line interventions and improve cGMP throughput. Hospitals and clinics represent the next-largest consumption base, pulling a wide portfolio—from LVP bags for hydration and nutrition to chemotherapy vials and emergency-use PFS—with purchasing criteria centered on workflow efficiency, dose accuracy, and safety-engineered devices to cut preparation time and contamination risk. Home healthcare & self-administration is the fastest-growing application: aging demographics, chronic disease prevalence, and payer pressure to de-institutionalize care are shifting share toward auto-injectors, pen cartridges, and wearable injectors, packaging that prioritizes usability, tamper evidence, and human-factors engineering. Across applications, share concentration reflects the premium placed on sterile barrier performance, container–drug compatibility, and end-user safety, with reimbursement and real-world adherence amplifying adoption of ready-to-use delivery formats.
United States Parenteral Products Packaging Market Accelerated by Biologics and Domestic Manufacturing Investments
The United States parenteral products packaging market is being reshaped by pharmaceutical industry investments, regulatory reforms, and advanced automation. Major players such as Eli Lilly and Johnson & Johnson are investing billions into domestic fill-finish capacity, which directly increases the demand for sterile vials, pre-filled syringes, and ready-to-use (RTU) systems. These formats are particularly valuable for biologics, personalized medicine, and biosimilars, where precision, sterility, and patient convenience are critical.
Government support is also reinforcing this market shift. Executive Order 14293 has streamlined approvals for new manufacturing facilities while tightening oversight of foreign imports, incentivizing companies to expand U.S.-based packaging operations. At the same time, the FDA is issuing guidance for combination products, enabling innovation where packaging doubles as a drug delivery system. Parallel to regulatory progress, the adoption of automation and robotics on secondary packaging lines is driving efficiency, reducing human error, and ensuring compliance with stringent sterility standards. Together, these developments are positioning the U.S. as a leader in high-value pharmaceutical packaging solutions.
China Parenteral Products Packaging Market Strengthened by Glass Preference and R&D Investments
The China parenteral products packaging market is expanding rapidly, driven by government-led modernization and a focus on safer drug delivery. Chinese authorities are urging pharmaceutical packaging companies to invest in R&D for innovative and eco-friendly materials, with an emphasis on stability and safety during long-term drug storage. A notable trend is the strong reliance on glass vials and ampoules, valued for their durability, non-reactivity, and transparency, making them the preferred material for biologics and vaccines.
The rise of China’s biologics and vaccine manufacturing capacity has amplified the need for advanced packaging solutions capable of ensuring sterility and drug integrity. With government backing, domestic companies are scaling up production to meet both local and export demand, while upgrading facilities to align with international quality standards. These trends confirm China’s growing role as a global hub for parenteral packaging innovation.
Germany Parenteral Products Packaging Market Driven by EU Regulations and Industry Leadership
The Germany parenteral products packaging market is heavily influenced by stringent EU sustainability and compliance regulations. The Packaging Act (VerpackG) and the EU Packaging and Packaging Waste Regulation (PPWR) are reshaping design standards by mandating recyclability, reduced waste, and increased use of recycled materials in secondary packaging. These rules are compelling manufacturers to balance sustainability with the uncompromising safety needs of parenteral drug packaging.
Germany is home to global leaders such as Gerresheimer and SCHOTT Pharma AG & Co. KGaA, which dominate in pharmaceutical glass and advanced polymer packaging solutions. Both companies continue to expand production capacity and pioneer new manufacturing technologies that enhance barrier protection and sterility. Compliance and quality remain central, as German and EU regulations demand the highest standards of product safety, traceability, and recyclability, making Germany a benchmark market for sustainable pharmaceutical packaging innovation.
India Parenteral Products Packaging Market Expanding Under PLI Scheme and Vaccine Growth
The India parenteral products packaging market is advancing rapidly due to strong government support and the expansion of pharmaceutical manufacturing. The Production Linked Incentive (PLI) scheme incentivizes investment in high-value pharmaceutical products, including sterile packaging for injectables. Meanwhile, the Free Essential Drugs Initiative under the National Health Mission has increased bulk procurement of generics, placing pressure on manufacturers to deliver efficient, high-quality packaging and streamlined supply chain systems.
The growth of biosimilars and vaccine production is further boosting demand for specialized vials, syringes, and IV bags. Domestic firms are adopting IT-backed supply chain technologies for real-time tracking and quality assurance, aligning with global compliance standards. With the rise of e-health programs and an expanding middle-class population, India’s pharmaceutical packaging industry is moving beyond volume-based production to focus on quality-driven, export-ready parenteral packaging solutions.
Japan Parenteral Products Packaging Market Advancing with Smart and Sustainable Technologies
The Japan parenteral products packaging market is distinguished by its focus on technological innovation and smart packaging integration. Japanese companies and research institutions are pioneering the use of RFID tags, temperature indicators, and connected devices to monitor sensitive biologics and vaccines throughout the supply chain. The government is actively funding projects under its Green Innovation framework, supporting the creation of eco-friendly and intelligent drug delivery packaging systems.
Events like the annual Combination Product Seminar underscore Japan’s emphasis on integrated solutions that merge packaging with drug delivery functionality. At the same time, firms such as Nippon Paper Industries and Oji Holdings are investing in sustainable materials and new production facilities, aiming to reduce the industry’s carbon footprint. With strong regulatory oversight and a culture of precision manufacturing, Japan continues to lead in next-generation parenteral packaging technologies that balance performance, safety, and sustainability.
Brazil Parenteral Products Packaging Market Supported by ANVISA Reforms and Local Innovation
The Brazil parenteral products packaging market is experiencing growth as regulatory modernization improves agility for manufacturers. The National Health Surveillance Agency (ANVISA) has introduced reforms such as RDC 843/2024, which unifies and simplifies procedures for packaging and product registration. This streamlined framework enables faster market entry for innovative packaging solutions and encourages investment from both domestic and multinational firms.
The simplified environment has already encouraged companies to introduce advanced packaging innovations tailored for local needs. Partnerships, such as those pioneered by Nestlé Brazil with renewable packaging solutions, demonstrate the potential for crossover between food and pharmaceutical packaging technologies. With its large domestic healthcare market and ongoing regulatory clarity, Brazil is positioning itself as a regional hub for parenteral packaging growth and innovation.
Parenteral Products Packaging Market Report Scope
Parenteral Products Packaging Market
Parameter
Details
Market Size (2025)
$29.2 Billion
Market Size (2034)
$69.4 Billion
Market Growth Rate
10.1%
Segments
By Product Type (Vials, Pre-filled Syringes, Ampoules, Cartridges, Bags & Bottles, Ready-to-Use Systems), By Material (Glass, Plastics & Polymers, Elastomers, Others), By Packaging Type (Primary, Secondary), By Drug Type (Small Molecules, Biologics & Biosimilars, Vaccines, Insulin, Ophthalmics, Other Drugs), By Application (Hospitals & Clinics, Pharmaceutical & Biotechnology Companies, Home Healthcare & Self-Administration)
Study Period
2019- 2024 and 2025-2034
Units
Revenue (USD)
Qualitative Analysis
Porter’s Five Forces, SWOT Profile, Market Share, Scenario Forecasts, Market Ecosystem, Company Ranking, Market Dynamics, Industry Benchmarking
US, Canada, Mexico, Germany, France, Spain, Italy, UK, Russia, China, India, Japan, South Korea, Australia, South East Asia, Brazil, Argentina, Middle East, Africa
Parenteral Products Packaging Market Segmentation
By Product Type
Vials
Pre-filled Syringes
Ampoules
Cartridges
Bags & Bottles
Ready-to-Use Systems
By Material
Glass
Plastics & Polymers
Elastomers
Others
By Packaging Type
Primary
Secondary
By Drug Type
Small Molecules
Biologics & Biosimilars
Vaccines
Insulin
Ophthalmics
Other Drugs
By Application
Hospitals & Clinics
Pharmaceutical & Biotechnology Companies
Home Healthcare & Self-Administration
Countries Analyzed
North America (US, Canada, Mexico)
Europe (Germany, UK, France, Spain, Italy, Russia, Rest of Europe)
Asia Pacific (China, India, Japan, South Korea, Australia, South East Asia, Rest of Asia)
South America (Brazil, Argentina, Rest of South America)
Middle East and Africa (Saudi Arabia, UAE, Rest of Middle East, South Africa, Egypt, Rest of Africa)
Top Companies in Parenteral Products Packaging Market
Gerresheimer AG
West Pharmaceutical Services, Inc.
SCHOTT Pharma AG & Co. KGaA
Stevanato Group
Nipro Corporation
SGD Pharma
AptarGroup, Inc.
Amcor Plc
Catalent, Inc.
Becton, Dickinson and Company
SiO2 Materials Science
Adelphi Healthcare Packaging
Datwyler Holding Inc.
DWK Life Sciences GmbH
* List Not Exhaustive
Methodology
USDAnalytics employs a comprehensive research methodology to deliver accurate and actionable insights into the Parenteral Products Packaging Market. Our approach integrates both primary and secondary research, leveraging proprietary databases, industry reports, company disclosures, and regulatory filings to evaluate market dynamics, competitive strategies, and growth drivers. We conduct in-depth interviews with key industry stakeholders—including manufacturers, distributors, pharmaceutical companies, and regulatory authorities—to validate trends such as the rise of biologics, pre-filled syringes, and patient-centric drug delivery systems. Quantitative data is analyzed using statistical and econometric models to determine market size, CAGR projections, and segment-wise opportunities, while qualitative assessments capture innovation trends, sustainability initiatives, and emerging technologies such as smart connected devices and barrier coatings. USDAnalytics combines regional market analyses, supply chain insights, and regulatory frameworks to provide a holistic view of market opportunities across North America, Europe, Asia-Pacific, and Latin America, enabling pharmaceutical packaging companies, investors, and healthcare stakeholders to make data-driven strategic decisions in a rapidly evolving parenteral packaging ecosystem.
Deliverables:
Comprehensive Market Research Report (PDF and Excel) with detailed tables, charts, and interactive visualizations.
Country-Specific Forecasts & Analysis.
Segment-Wise Revenue Forecasts (2025–2034).
Competitive Analysis, Benchmarking, and SWOT Profiles.
Recent Developments & Innovation Tracker.
Executive Summary & Analyst Commentary.
Post-Purchase Analyst Support for Client-Specific Questions and Custom Data Requirements.
Table of Contents: Parenteral Products Packaging Market
1. Executive Summary
1.1. Market Highlights
1.2. Key Findings
1.3. Global Market Snapshot
2. Parenteral Products Packaging Market Landscape & Outlook (2025–2034)
2.1. Introduction to Parenteral Products Packaging Market
2.2. Market Valuation and Growth Projections (2025–2034)
2.3. Market Drivers and Restraints
2.4. Regulatory Environment and Compliance Landscape
2.5. Strategic Investment and Expansion Trends
3. Innovations Reshaping the Parenteral Products Packaging Market
3.1. Trend: Strategic Onshoring of Glass Packaging Manufacturing for Supply Chain Resilience
3.2. Trend: Accelerated Adoption of Ready-to-Use Systems and Integrated Delivery Devices
3.3. Opportunity: Development of Novel Containment Solutions for High-Potency APIs (HPAPIs)
3.4. Opportunity: Innovation in Materials and Connectivity for At-Home Drug Administration
4. Competitive Landscape and Strategic Initiatives
4.1. Mergers, Acquisitions and Strategic Alliances
4.2. R&D and Material Innovation
4.3. Sustainability and Strategies
4.4. Market Expansion and Regional Focus
5. Market Share and Segmentation Insights: Parenteral Products Packaging Market
5.1. By Product Type
5.1.1. Vials
5.1.2. Pre-filled Syringes
5.1.3. Ampoules
5.1.4. Cartridges
5.1.5. Bags & Bottles
5.1.6. Ready-to-Use Systems
5.2. By Material
5.2.1. Glass
5.2.2. Plastics & Polymers
5.2.3. Elastomers
5.2.4. Others
5.3. By Packaging Type
5.3.1. Primary
5.3.2. Secondary
5.4. By Drug Type
5.4.1. Small Molecules
5.4.2. Biologics & Biosimilars
5.4.3. Vaccines
5.4.4. Insulin
5.4.5. Ophthalmics
5.4.6. Other Drugs
5.5. By Application
5.5.1. Hospitals & Clinics
5.5.2. Pharmaceutical & Biotechnology Companies
5.5.3. Home Healthcare & Self-Administration
6. Country Analysis and Outlook of Parenteral Products Packaging Market
6.1. United States
6.2. Canada
6.3. Mexico
6.4. Germany
6.5. France
6.6. Spain
6.7. Italy
6.8. UK
6.9. Russia
6.10. China
6.11. India
6.12. Japan
6.13. South Korea
6.14. Australia
6.15. South East Asia
6.16. Brazil
6.17. Argentina
6.18. Middle East
6.19. Africa
7. Parenteral Products Packaging Market Size Outlook by Region (2025-2034)
7.1. North America Parenteral Products Packaging Market Size Outlook to 2034
7.1.1. By Product Type
7.1.2. By Material
7.1.3. By Packaging Type
7.1.4. By Drug Type
7.2. Europe Parenteral Products Packaging Market Size Outlook to 2034
7.2.1. By Product Type
7.2.2. By Material
7.2.3. By Packaging Type
7.2.4. By Drug Type
7.3. Asia Pacific Parenteral Products Packaging Market Size Outlook to 2034
7.3.1. By Product Type
7.3.2. By Material
7.3.3. By Packaging Type
7.3.4. By Drug Type
7.4. South America Parenteral Products Packaging Market Size Outlook to 2034
7.4.1. By Product Type
7.4.2. By Material
7.4.3. By Packaging Type
7.4.4. By Drug Type
7.5. Middle East and Africa Parenteral Products Packaging Market Size Outlook to 2034
7.5.1. By Product Type
7.5.2. By Material
7.5.3. By Packaging Type
7.5.4. By Drug Type
8. Company Profiles: Leading Players in the Parenteral Products Packaging Market
8.1. Gerresheimer AG
8.2. West Pharmaceutical Services, Inc.
8.3. SCHOTT AG
8.4. Stevanato Group
8.5. Nipro Corporation
8.6. SGD Pharma
8.7. AptarGroup, Inc.
8.8. Berry Global Inc.
8.9. Amcor Plc
8.10. Catalent, Inc.
8.11. Becton, Dickinson and Company
8.12. SiO2 Materials Science
8.13. Adelphi Healthcare Packaging
8.14. Datwyler Holding Inc.
8.15. DWK Life Sciences GmbH
9. Methodology
9.1. Research Scope
9.2. Market Research Approach
9.3. Market Sizing and Forecasting Model
9.4. Research Coverage
9.5. Data Horizon
9.6. Deliverables
10. Appendix
10.1. Acronyms and Abbreviations
10.2. List of Tables
10.3. List of Figures
Parenteral Products Packaging Market Segmentation
By Product Type
Vials
Pre-filled Syringes
Ampoules
Cartridges
Bags & Bottles
Ready-to-Use Systems
By Material
Glass
Plastics & Polymers
Elastomers
Others
By Packaging Type
Primary
Secondary
By Drug Type
Small Molecules
Biologics & Biosimilars
Vaccines
Insulin
Ophthalmics
Other Drugs
By Application
Hospitals & Clinics
Pharmaceutical & Biotechnology Companies
Home Healthcare & Self-Administration
Countries Analyzed
North America (US, Canada, Mexico)
Europe (Germany, UK, France, Spain, Italy, Russia, Rest of Europe)
Asia Pacific (China, India, Japan, South Korea, Australia, South East Asia, Rest of Asia)
South America (Brazil, Argentina, Rest of South America)
Middle East and Africa (Saudi Arabia, UAE, Rest of Middle East, South Africa, Egypt, Rest of Africa)
The global Parenteral Products Packaging Market is projected to grow from $29.2 billion in 2025 to $69.4 billion by 2034, reflecting a robust CAGR of 10.1%. Growth is driven by rising biologics production, increasing use of pre-filled syringes, patient-centric delivery devices, and the expanding adoption of ready-to-use injectable systems across hospitals, clinics, and home healthcare.
Vials lead the market with approximately 35% share, due to their versatility and regulatory validation. Pre-filled syringes (~30%) are the fastest-growing segment, propelled by self-administration trends and patient-centric care. Ampoules, cartridges, and bags & bottles continue to serve niche applications, while ready-to-use systems are gaining premium market adoption for critical care and biologics.
The increasing prevalence of biologics and biosimilars demands advanced containment systems, including high-quality glass vials, elastomer stoppers, and polymer syringes. These products ensure drug stability, prevent extractables/leachables, and maintain sterility, while also supporting patient-centric delivery systems like auto-injectors and wearable injectors, ultimately improving safety and adherence.
Key growth regions include the U.S., China, Germany, India, and Japan. In the U.S., domestic fill-finish expansions and biologics production accelerate demand. China emphasizes glass vials and R&D for safer injectables. Germany follows strict EU regulations for sustainability and safety, while India leverages the PLI scheme and vaccine expansion. Japan focuses on smart, connected packaging solutions.
Emerging innovations include ready-to-use systems, smart connected injectors, wearable delivery devices, and high-barrier glass/plastic materials. These technologies enhance patient safety, dosing accuracy, and supply chain traceability, while minimizing errors and environmental impact. Adoption of digital tagging (RFID/QR codes) and sustainable elastomers further strengthens compliance and circular economy alignment.
More Healthcare and Pharmaceutical Packaging Reports